Crypto and gold led August; U.S. equities were selective. BTC gained +25.04% and gold +9.43%, while U.S. small caps, measured by the Russell 2000 ETF (IWM), added just +0.94%. Crypto gains reached well beyond BTC, while gold rose without a broad Treasury rally.
Cross Asset Market
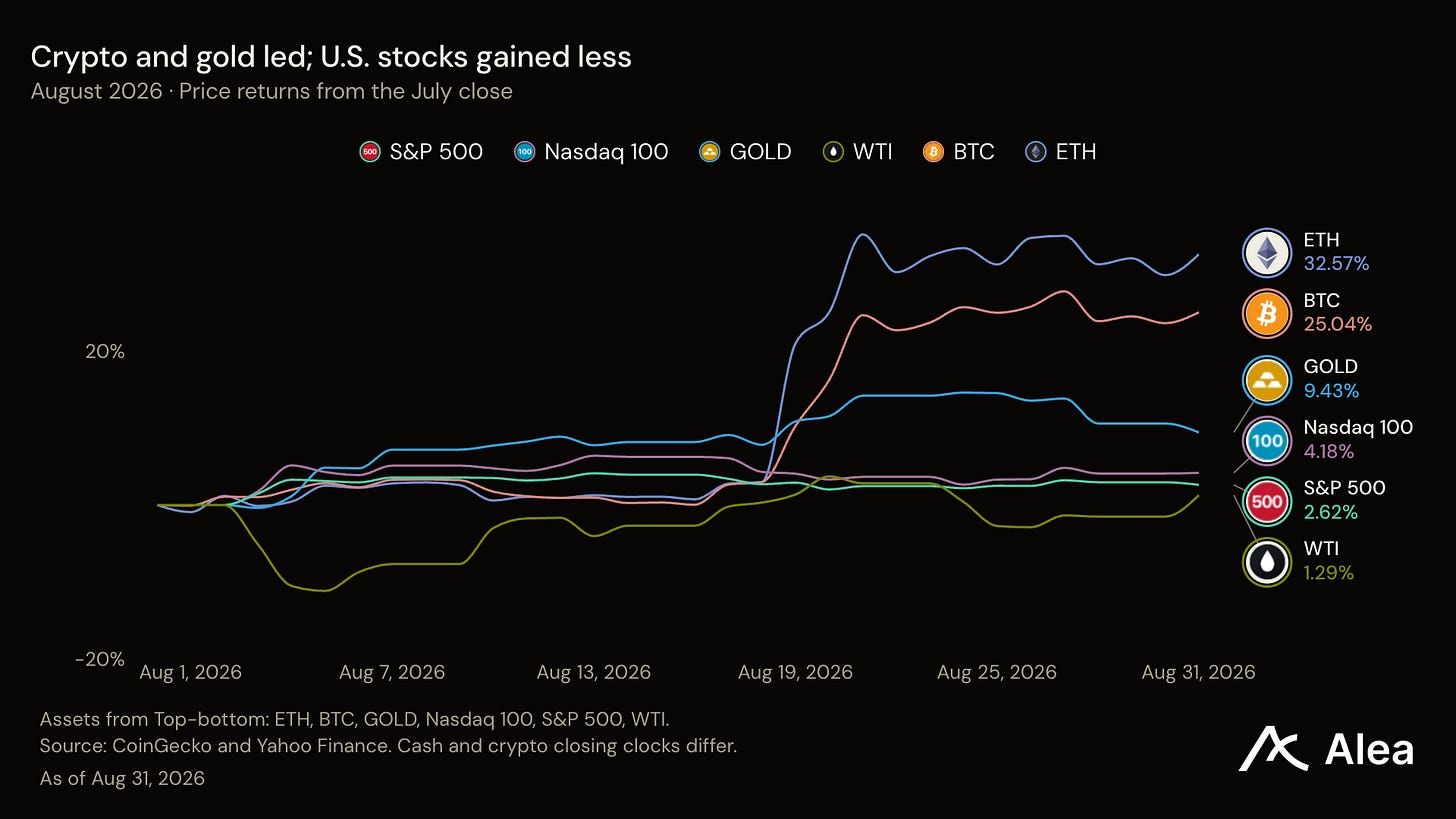
Takeaways
Rising tide for crypto; selectivity in stocks. Most tokens rose; idiosyncratic earnings and news characterized equities.
Gold rose alongside steady bond yields. The 10-year finished unchanged at 4.75%.
Token economics become more transparent. Ether.fi starts recording buybacks; Ethena proposed them behind a supply threshold.
The commodity story extended beyond metals. Cocoa, sugar, and wheat outpaced gold.
Macro
July’s PCE prices rose 0.2%, but annual headline inflation remained 3.7% and core inflation 3.3%. Real consumer spending was flat. The BEA release paired flat demand with persistent inflation.
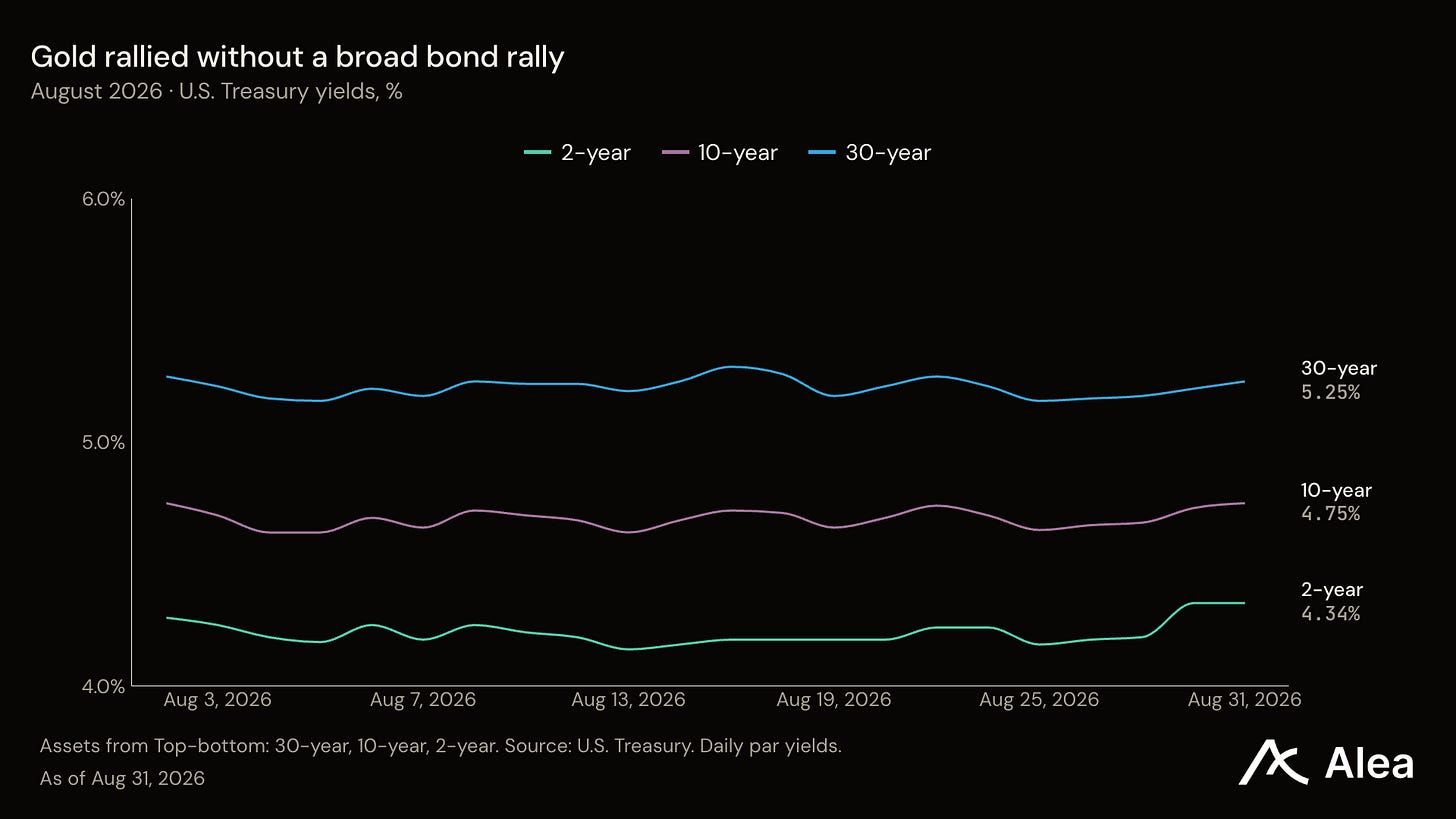
The 2-year yield rose 6 basis points to 4.34%; the 10-year ended where it began. That fits the Fed’s August 28 emphasis on price stability.
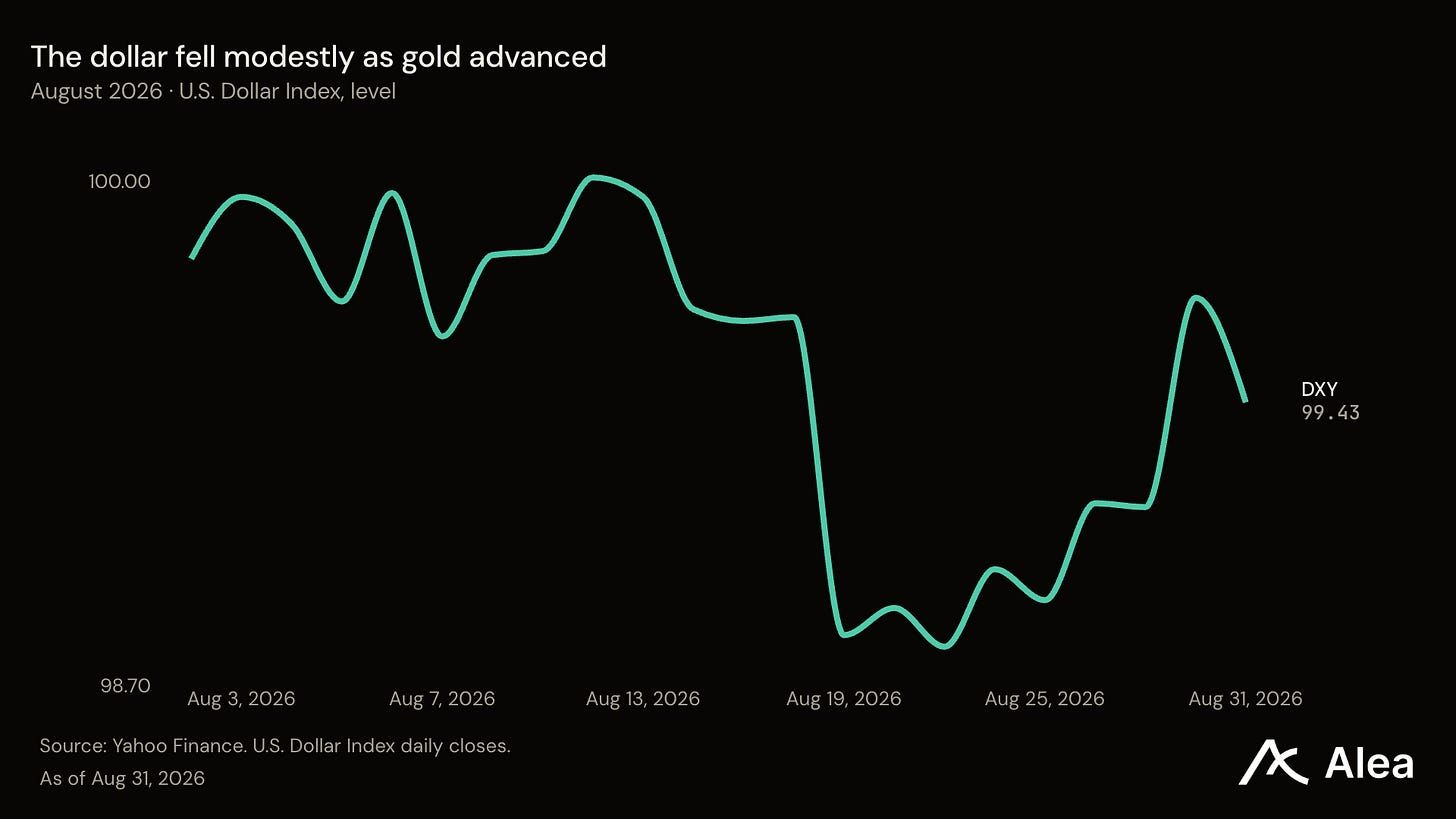
The dollar index fell just −0.37%. Gold outpaced the currency move by a wide margin. September’s inflation releases will help establish whether short-term yields can follow the dollar lower.
Crypto
ETH gained +32.57%, ahead of BTC’s +25.04%. The advance reached well beyond those two: the median eligible token rose +16.76%.
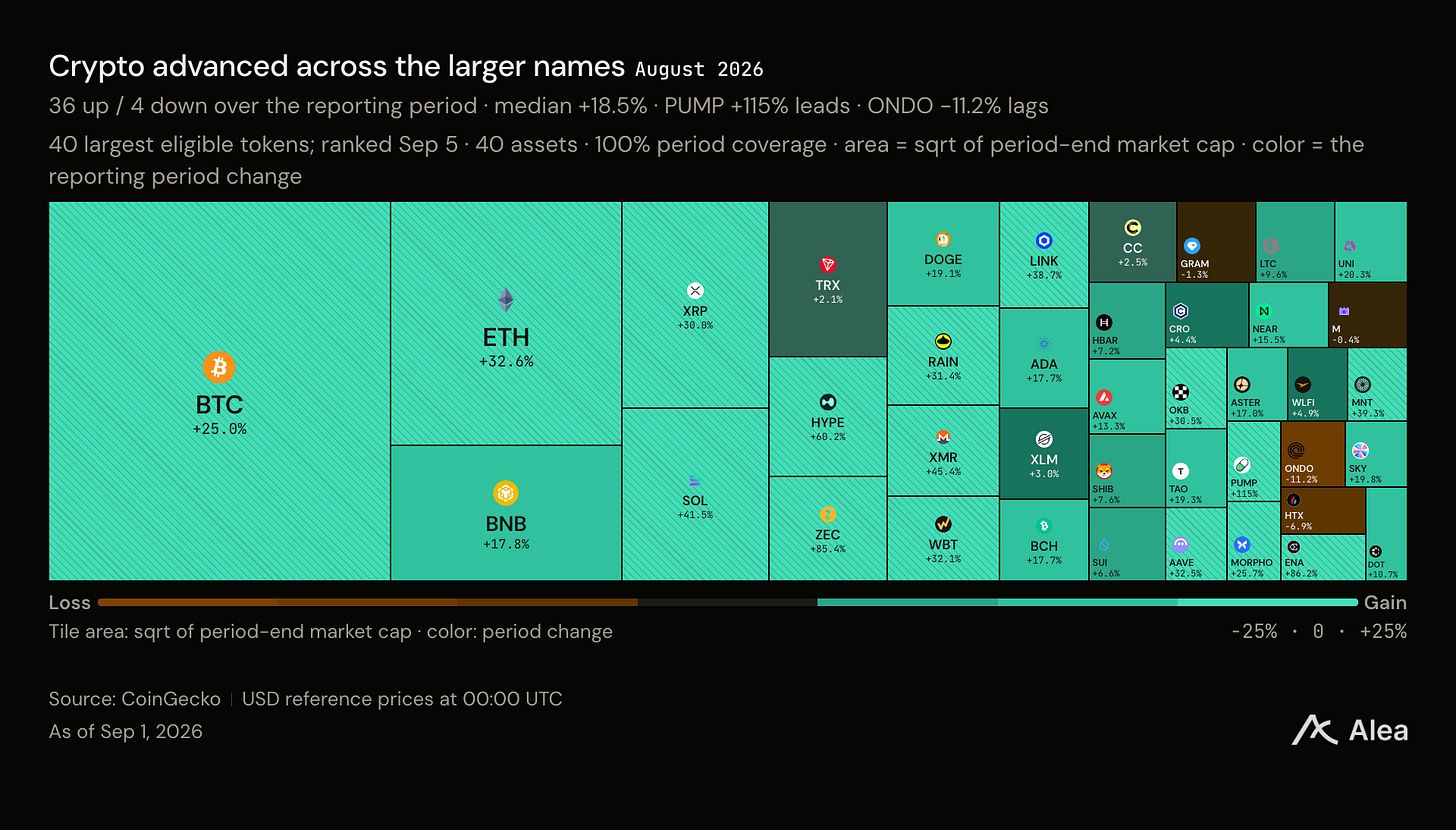
Broad participation still left meaningful exceptions. Pump.fun gained +115.09%, Ethena +86.16%, and Zcash +85.40%; Ondo lost −11.23%. Token selection still mattered within a rising market.
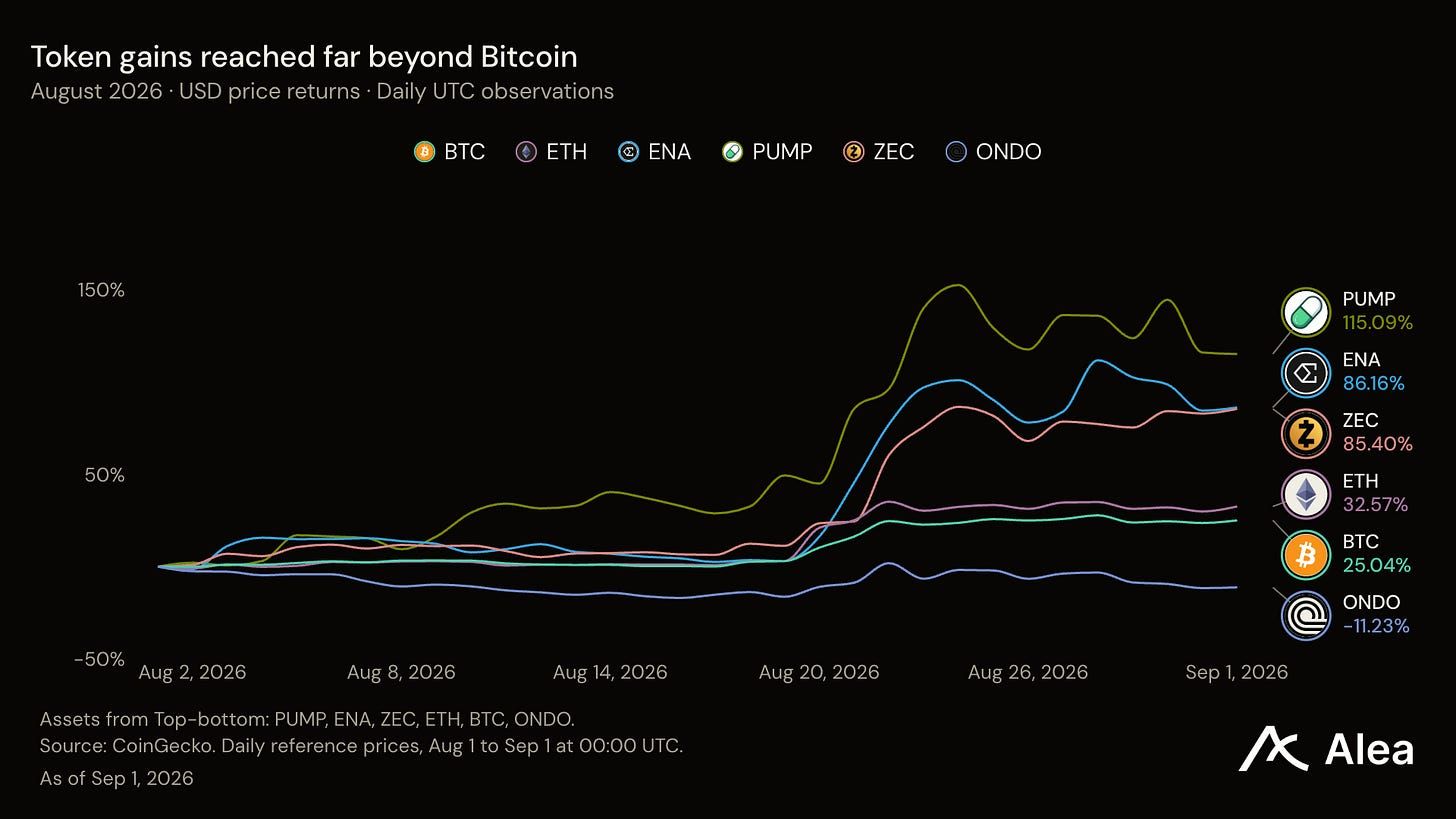
Ethena. Its August 27 fee proposal assigns 95% of net revenue to buybacks at the first tier, after the Foundation’s 5% gross-revenue allocation. Activation begins at $7.5B of USDe supply, versus $4.07B stated in the proposal: roughly 84% more supply is needed. Read Alea’s ENA’s Claim on Ethena Is Still Contingent.
Ether.fi. Its August product expansion broadened the customer relationship; ETHFI rose +36.95%. Revenue after rewards and servicing costs will show how much value that expansion retains. Read Alea’s ETHFI’s Buyback Vote.
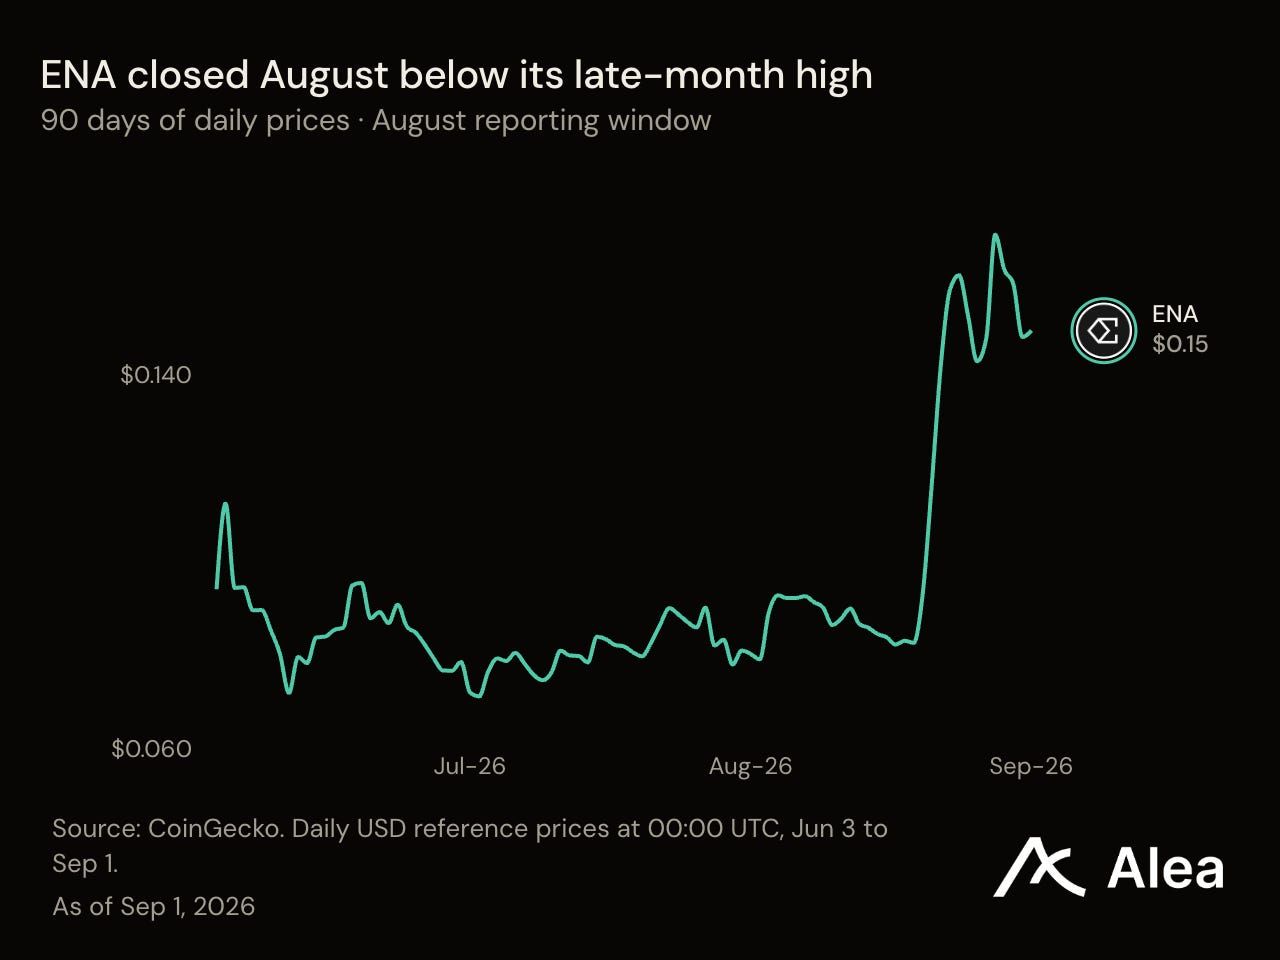
ENA ended August about 12.1% below its August 27 UTC closing price despite the month’s large gain. USDe supply growth and executed purchases will establish progress toward the proposed buybacks.
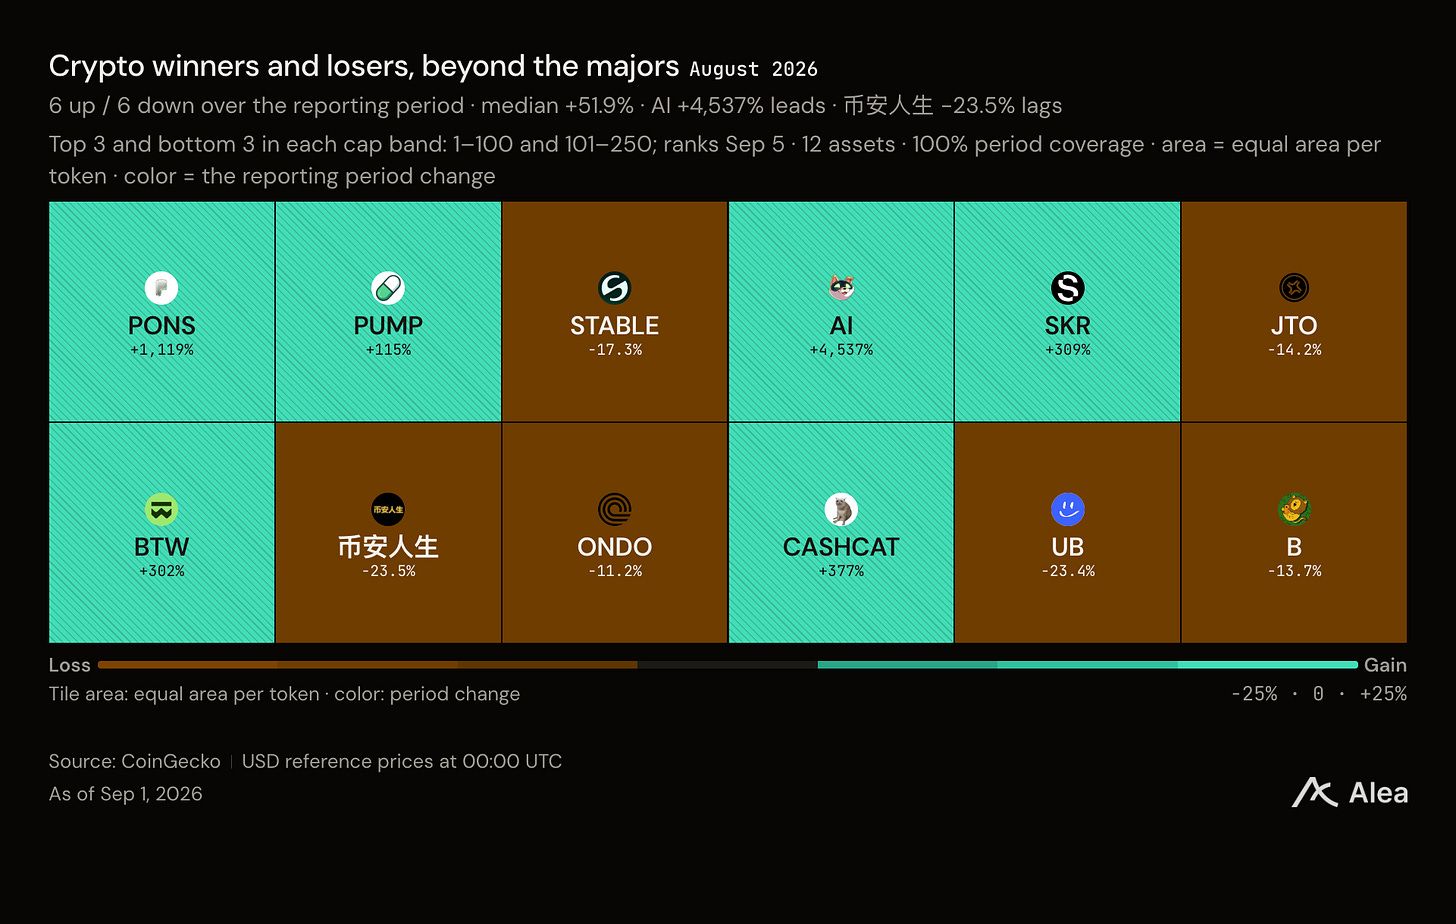
Pons rose +1,119%, making its ending price roughly 12 times the starting price.
Equities
The S&P 500 gained +2.62% and Nasdaq 100 +4.18%, well ahead of IWM. Within the below 49-stock cohort, Coinbase, Robinhood, and Freeport-McMoRan led at +28.62%, +21.08%, and +20.93%. GE, UnitedHealth, and Walmart lagged at −6.77%, −6.03%, and −5.69%.
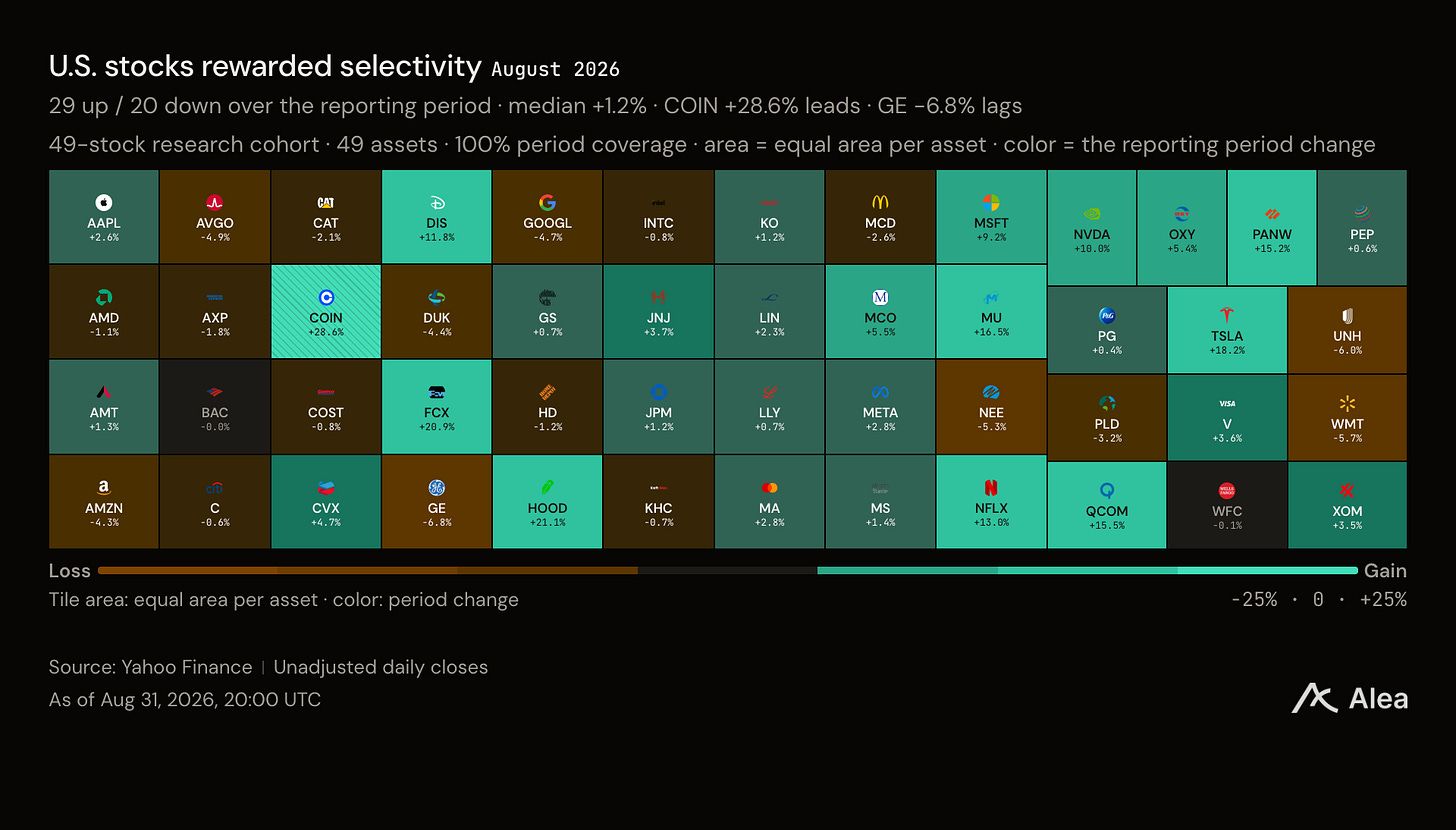
Nvidia gave AI demand an earnings anchor: quarterly revenue of $96.2B, up 106% year over year, and a $108B next-quarter outlook. That midpoint requires another 12.2% sequential increase. NVDA rose +9.98%, while the semiconductor ETF SOXX added +1.22%. The earnings release supports Nvidia’s growth story; the sector return shows how unevenly the rally spread. Read Alea’s When the AI Trade Became a Memory Trade.
Commodities
Gold’s +9.43% and silver’s +14.98% were only part of the advance. 23 of 28 nearby futures contracts rose. Cocoa gained +23.22%, sugar +21.49%, and Chicago wheat +18.34%; orange juice fell −23.04%, lean hogs −15.35%, and feeder cattle −7.64%. Food and industrial input costs moved in different directions.
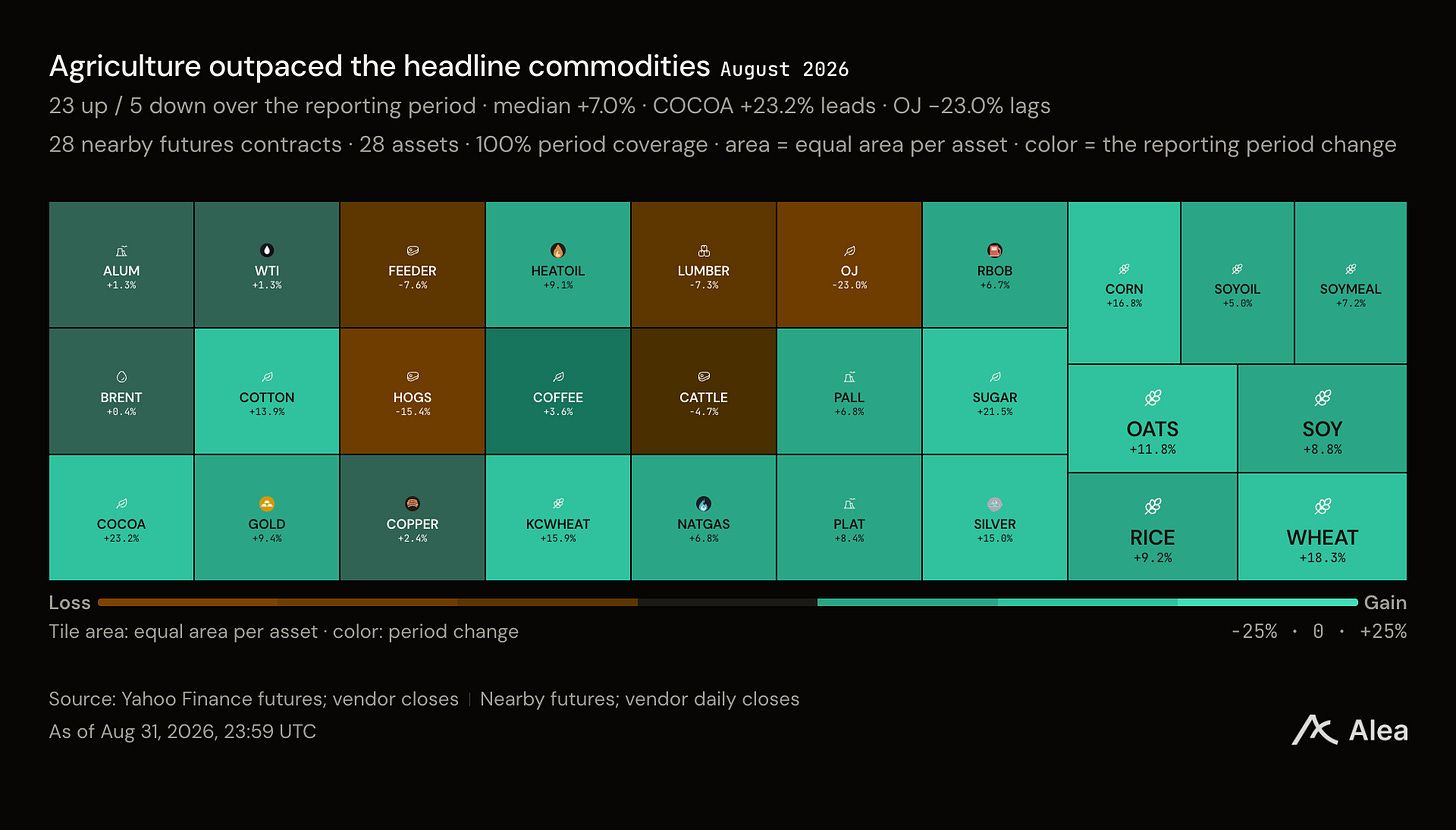
WTI added just +1.29%. August’s commodity inflation pressure came chiefly from selected food and metal contracts, with far less support from oil. Delivery dates and contract rolls also affect nearby futures prices.
Method: cash prices compare July 31 and August 31 closes. CoinGecko reference prices run from August 1 to September 1 at 00:00 UTC, capturing August’s UTC closes. Crypto excludes pegged assets and tokenized funds, securities, and commodities, requires both prices, and uses a $1M closing-day volume floor. Equity breadth covers a 49-stock research cohort. Futures use vendor daily closes. Sources: CoinGecko, Yahoo Finance, U.S. Treasury.

Read our Weekly Pulse, Alea’s full-week strategic synthesis across macro and the major liquid markets, delivered weekly.
Alea combines independent research with live protocol data for financial institutions and protocol teams. We clarify market structure and test investment cases. The same work communicates economic value with precision.