跳至内容

价格下跌,代币倍增

2026年10月14日11 min

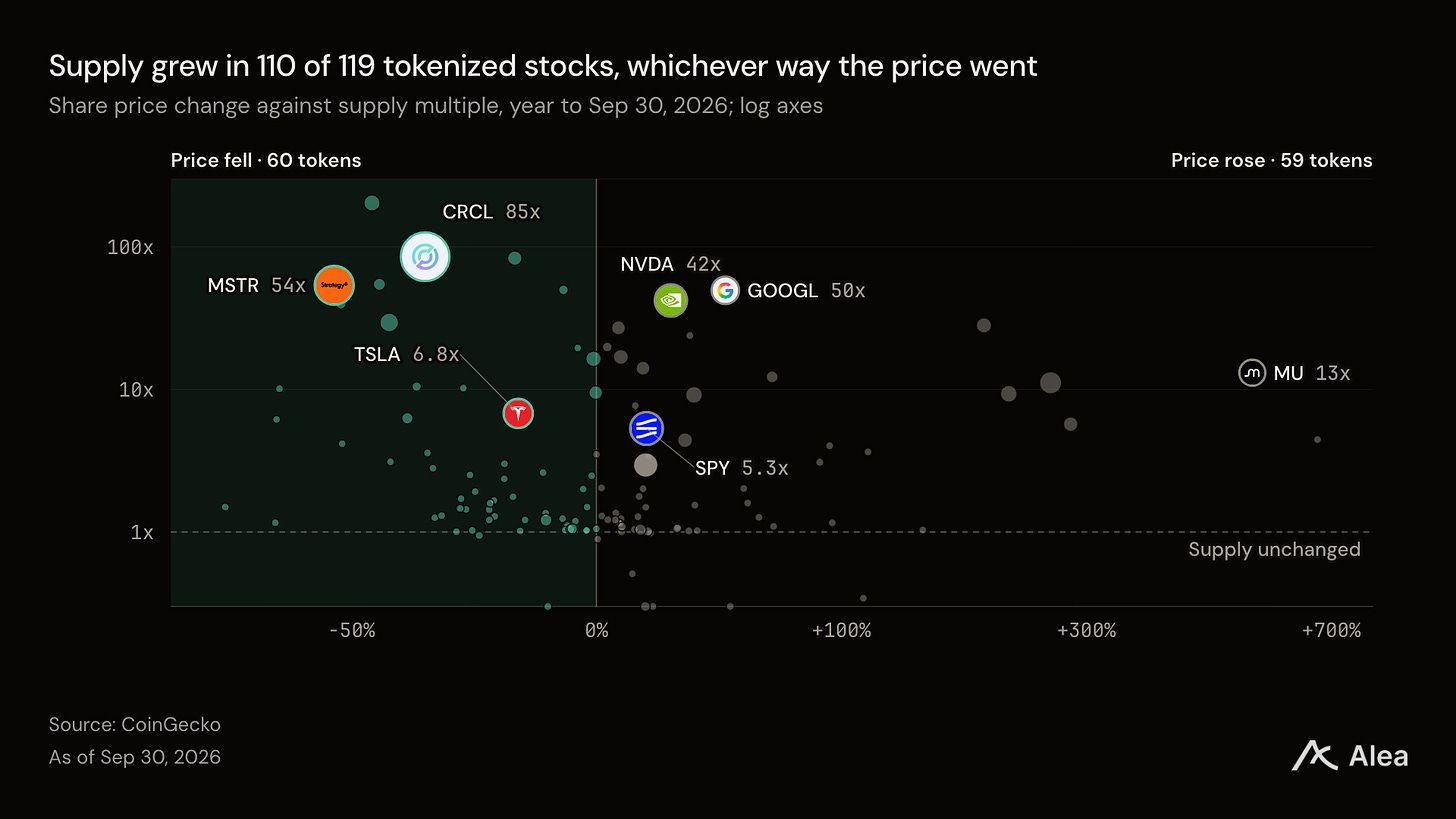
Circle 的股价 下跌 38%,截至 9 月 30 日的一年。它的代币供应量 增长 85 倍。这就是整个代币化股票市场的缩影:价格下跌,而代币数量激增。 包装股票 增长 7.6 倍 至 31.4 亿美元。一年前已存在的代币新增了 +18.9 亿美元 的供应;股价变动减少了 -1.21 亿美元。发行方铸造代币,新平台上市这些代币。与价格无关,人们对链上现货代币化股权有大量需求。
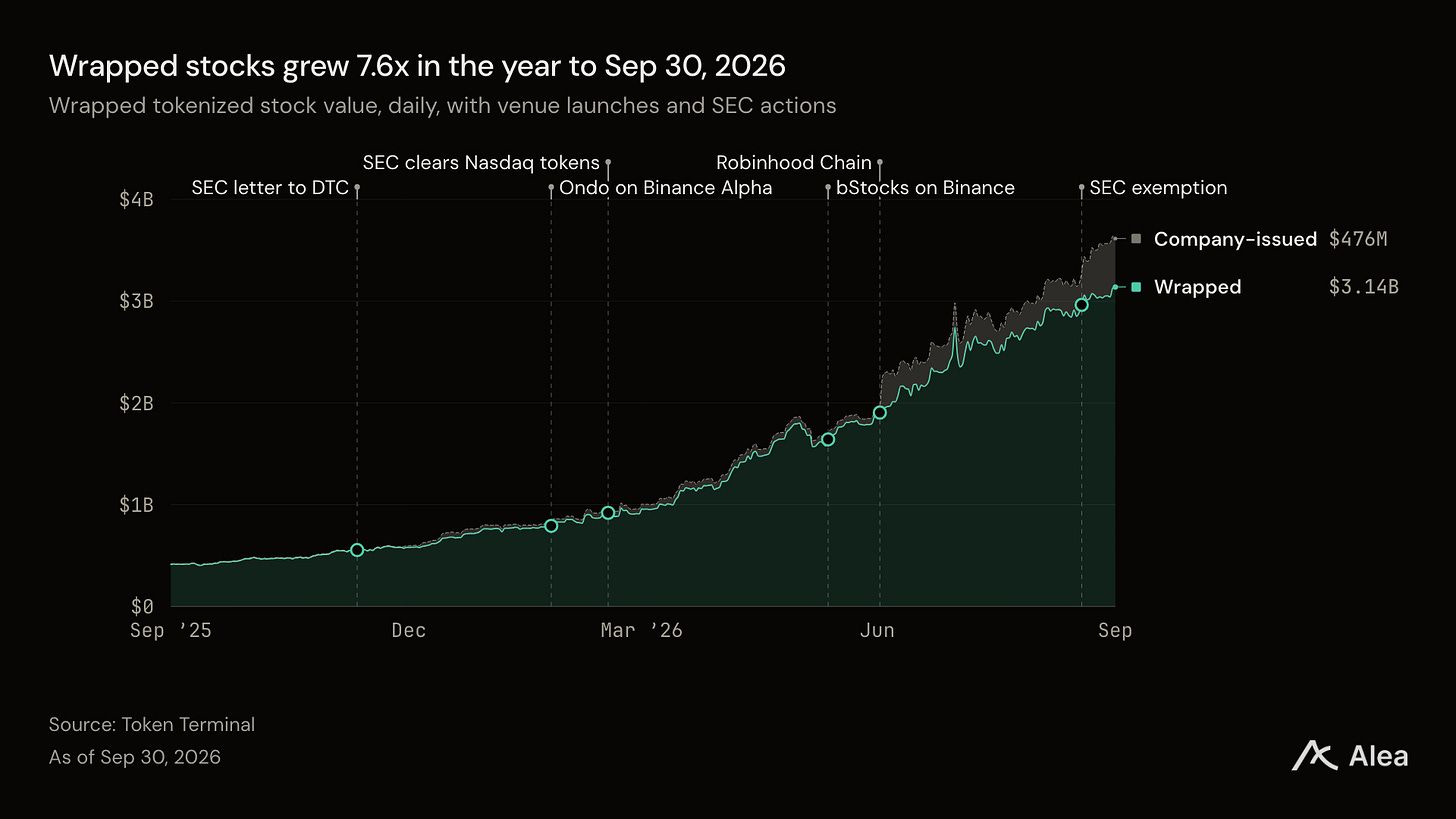
Area chart of wrapped tokenized stock value from Sep 30, 2025 to Sep 30, 2026, rising from $413M to $3.14B, with $476M of company-issued shares on top. Labels above the plot name three venue launches (Ondo on Binance Alpha, bStocks on Binance, Robinhood Chain) and three SEC actions at their dates. Token Terminal data.
The steepest weeks followed exchange launches, and company-issued shares add $476M on top of the wrapped total. Wrapped stocks are tokens an issuer mints against shares it holds. Shares that companies issue onchain through Securitize, Superstate, or Nyala count apart.

要点

  • 新增供应构建了市场。 一年前已存在的代币 录得 18.9 亿美元的新增供应,而价格变动减少了 1.21 亿美元。在 119 个代币中,有 110 个的供应量增长,无论股价如何变动。

  • 交易所上市决定了增长节奏。 每个新平台开放后的一周内,包装价值 增长 8% 至 10%,而中位数周增长为 3.9%。SEC 行动 关闭 后的每周增长均低于该中位数,增速低于 3%。

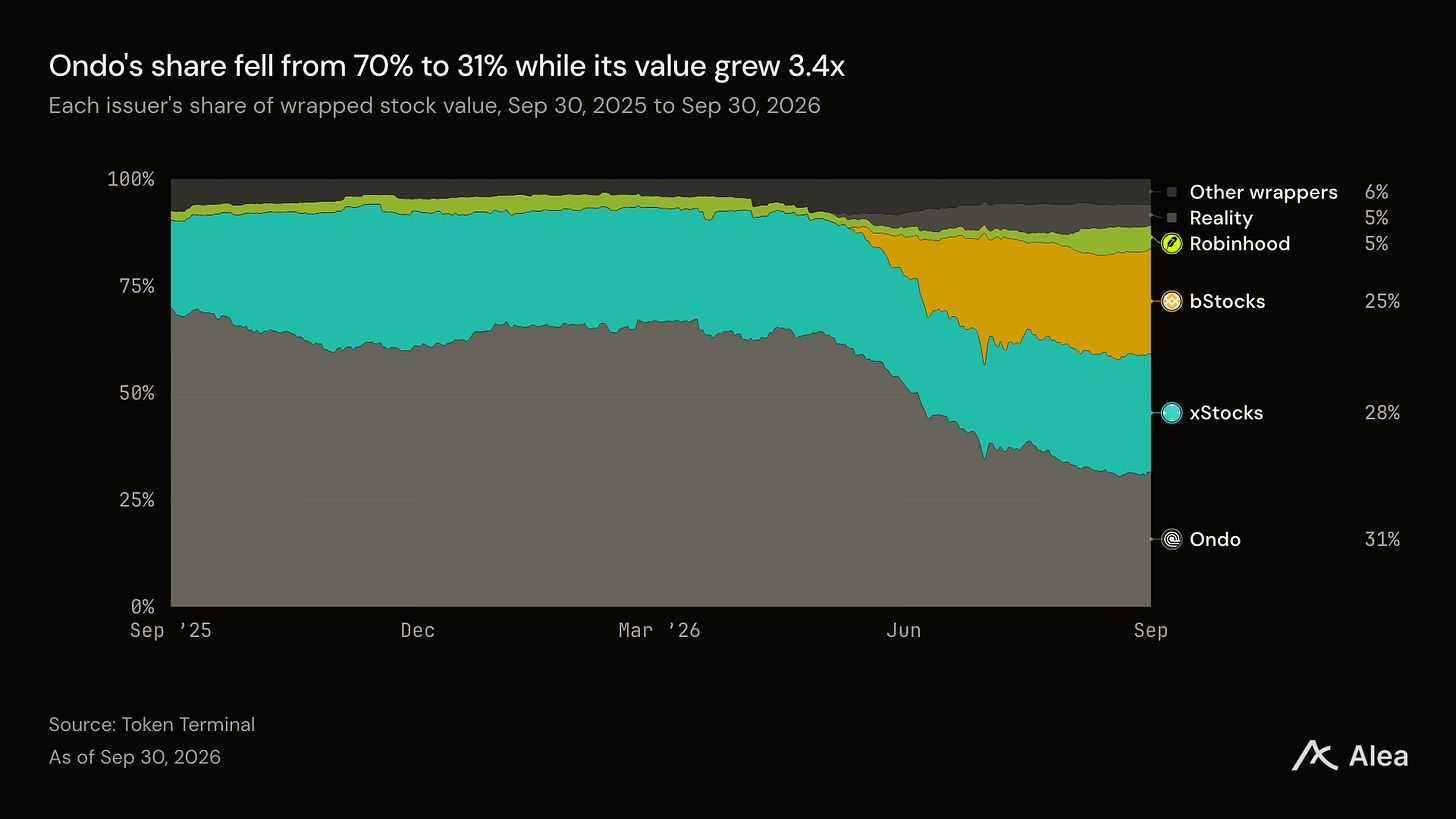
  • 三家发行方现已瓜分市场。 Ondo 的价值 增长 3.4 倍,而 xStocks 和 bStocks 各自新增超过 7.7 亿美元。三家发行方年末各占包装价值的 25% 至 31%。

  • 持有人既能获得股票价格,又能享受周末市场。 代币在典型交易日收盘价与股票相差仅 8 个基点。在平均周末日,它们交易额达 2.84 亿美元,而所有股票平台均已关闭。

  • SEC 在离岸市场之外开辟了第二个美国市场。 其 9 月 17 日豁免允许代币携带股票的投票权和分红,最早从 2026 年 10 月 17 日起生效。Ondo 已在美国发行两只此类代币。

现有代币 新增 18.9 亿美元 供应

包装股票是发行方在托管人处持有股票后铸造的代币,这意味着其链上总价值通过两种方式变化:股价变动,或发行方铸造或赎回代币。截至 9 月 30 日的一年,铸造几乎贡献了全部增长。

一年前已存在的 120 个代币 录得 18.9 亿美元的新增供应,而同一代币的价格变动减少了 1.21 亿美元,此后上市的 53 个代币 又新增 9.95 亿美元。现有代币的新增供应占全年增长的 68%。

市场的每种统计口径均显示至少五倍增长。本期包装系列 收于 31.4 亿美元,为期初的 7.6 倍。最广口径还包括公司自行在链上发行的股票,收于 32.1 亿美元,为期初的 5.0 倍。
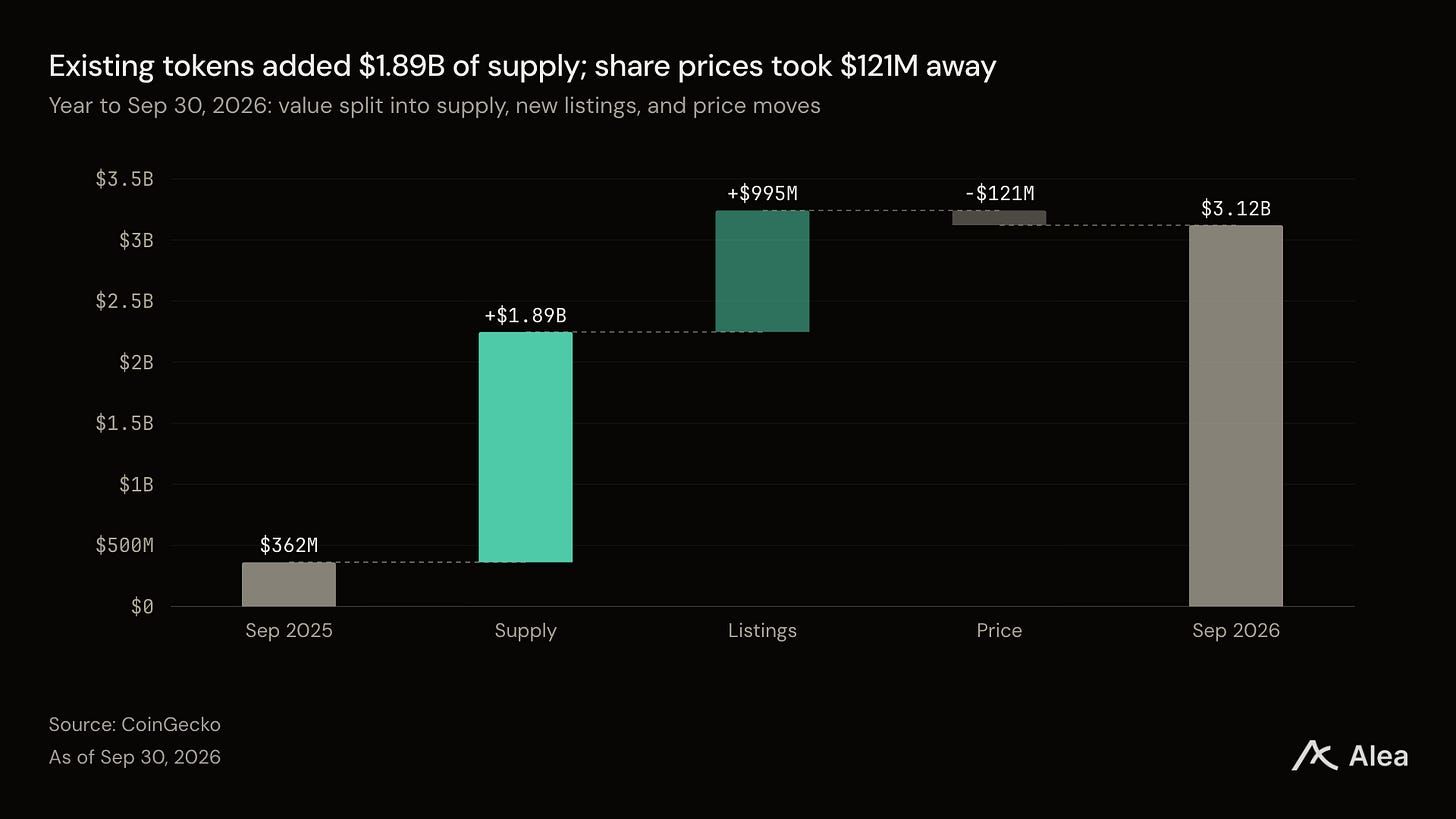
Waterfall chart of tokenized stock value from $362M to $3.12B over the year to Sep 30, 2026: supply on existing tokens adds $1.89B, new listings $995M, and price moves subtract $121M. CoinGecko data.
New supply on tokens that already existed explains most of the year’s rise, and price moves subtracted from it. The supply effect is average price times the change in supply, and the price effect is average supply times the change in price.
Scatter chart of 119 tokenized stocks and ETFs, share price change on the horizontal axis and token supply multiple on the vertical axis, both log scales, year to Sep 30, 2026. CoinGecko data.
Token supply rose for falling and rising shares alike, including Circle, Strategy, and Coinbase, whose shares fell. Each observation combines all issuers’ tokens of one share; token values are measured on Sep 30.

股价下跌并未阻止新增供应增长。在年初和年末均有代币的 119 只股票和 ETF 中,有 60 只股价下跌;其中 58 只的供应量增长。例如,Strategy 的股价在截至 9 月 30 日的一年 下跌 52%,而其代币供应量 增长 54 倍。

股价跌幅最大的几周,铸造速度最快。在 25 只最大的代币化股票中,当周股价 下跌 10% 或以上时,供应量中位数周增长为 4.9%。当股价变动小于 5% 时,该数字为 1.4%。

最快的几周紧随交易所上线

每个季度新增价值均高于上一季度,第三季度结束时达 12.4 亿美元。

Ondo 于 2026 年 2 月 24 日在 Binance Alpha 上线 其代币化股票和 ETF。Binance 于 6 月 11 日 上线 bStocks 交易。Robinhood 于 7 月 1 日 宣布 其链和股票代币。在这些日期后的一周内,包装价值 增长 7.7% 至 10.1%,这三周均进入全年 359 个七天窗口的前五分之一。

SEC 行动对价值的影响小于上市。SEC 工作人员于 2025 年 12 月 11 日向 DTC 发布 信函,委员会于 3 月 18 日 批准 Nasdaq 的代币化交易。此后一周,以及 9 月 17 日豁免后,增长 2.6% 至 2.7%,低于 3.9% 的中位数周增长。规则决定谁能进入美国平台。本年度的供应增长跟随上市步伐。
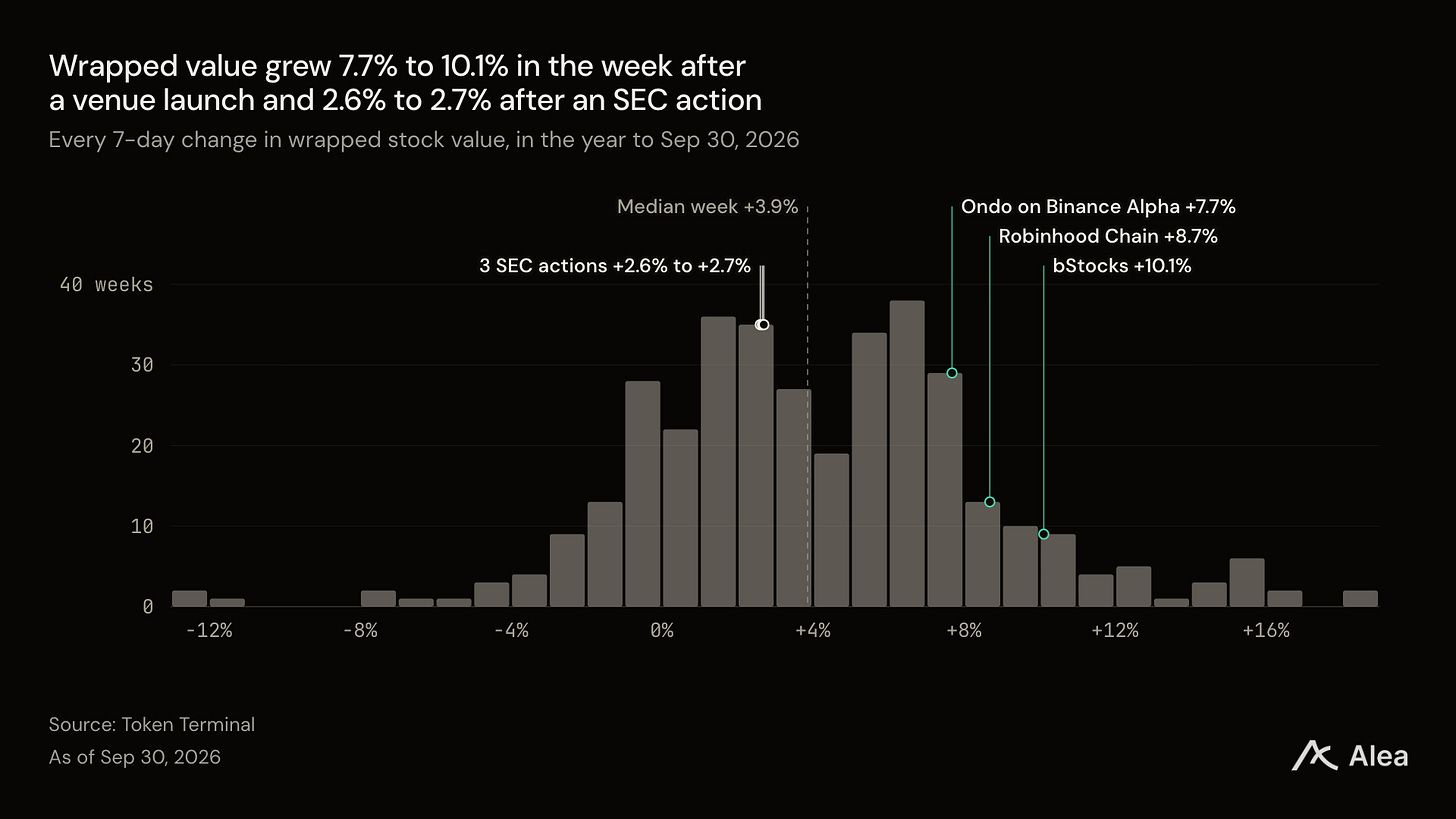
Histogram of 359 seven-day changes in wrapped stock value, year to Sep 30, 2026, with the median week at 3.9% and the weeks after three venue launches and three SEC actions marked. Token Terminal data.
Weeks after a venue launch sat in the upper tail of the year, and weeks after an SEC action sat just below the middle. Each week opens on a day and closes seven days later, and an event’s week opens on the event’s day.

三家发行方 贡献全年 27.3 亿美元中的 22.5 亿美元

三家发行方均通过交易所或零售应用销售。

Backed 于 2025 年 6 月 30 日在 Kraken 和 Bybit 上线 xStocks,2025 年 12 月 2 日 Kraken 宣布 将收购该公司。Ondo 通过 Binance Alpha 和 Bitget 销售。bStocks 仅通过 Binance 铸造和赎回,从 6 月的零增长至包装价值的四分之一。Binance 的 bStocks 也是首个达到 10 亿美元里程碑的代币。

Ondo 的代币价值在一年内增长 3.4 倍,而其市场份额从 70% 降至 31%。xStocks 增长 10 倍,bStocks 在上线四个月内即占据市场四分之一。三家大型发行方现已瓜分原本由 Ondo 主导的市场。
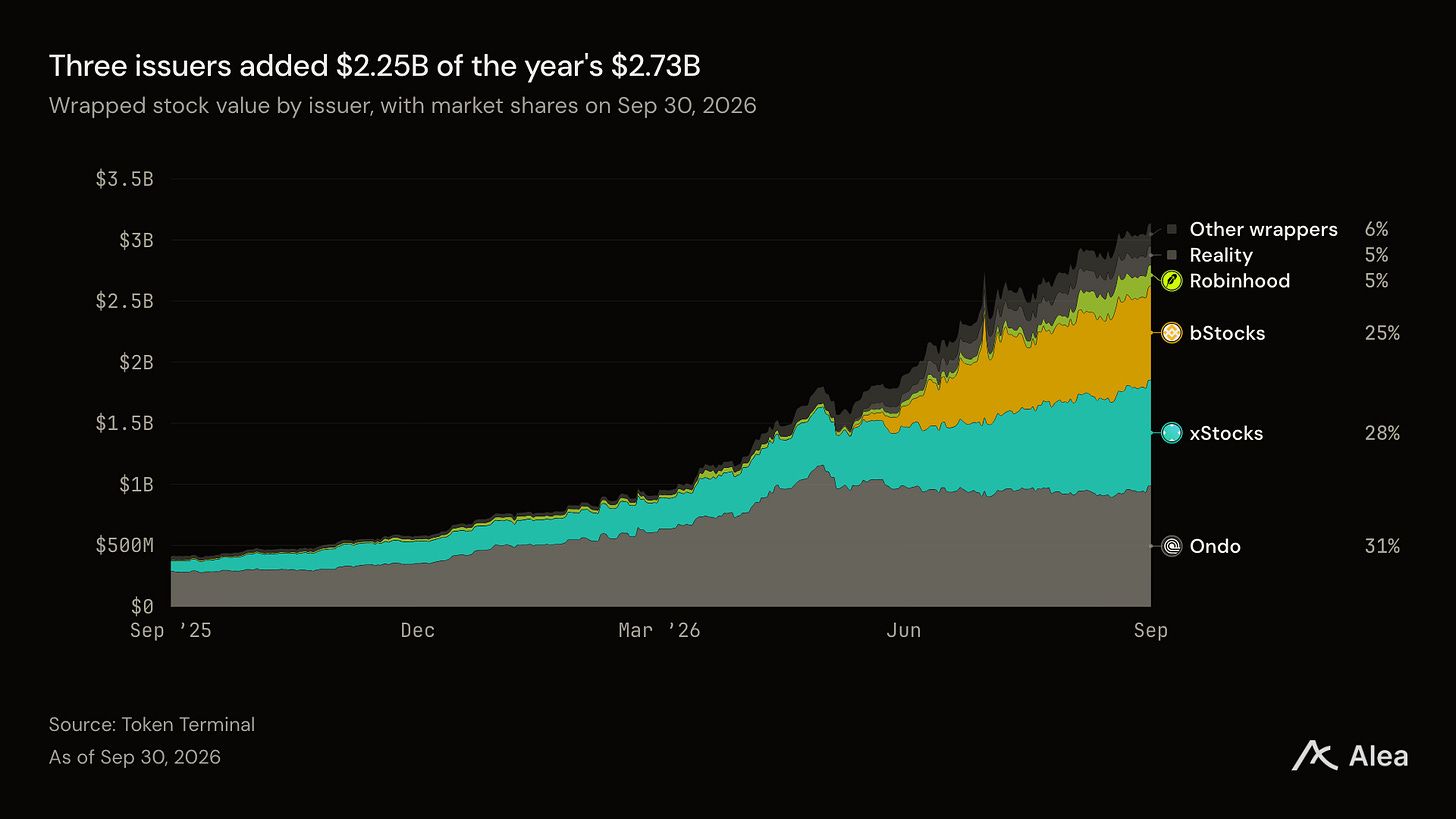
Stacked area chart of wrapped stock value by issuer, Sep 30, 2025 to Sep 30, 2026. Ondo ends at 31%, xStocks at 28%, and bStocks at 25% of value. Token Terminal data.
Ondo ended the year as the largest issuer at 31% of wrapped value, ahead of xStocks at 28% and bStocks at 25%. The issuers after the top five are summed.
Stacked share chart of wrapped stock value by issuer, Sep 30, 2025 to Sep 30, 2026, with Ondo falling from 70% to 31% as xStocks, bStocks, and Robinhood grow. Token Terminal data.
bStocks reached a quarter of the market within four months of its June launch. Ondo's share fell from 70% to 31% over the year as competing issuers expanded.

费用取决于代币和交易路径。Backed 列出 SPYx(其标普 500 代币)的发行或赎回费用最高 0.50%。标的 SPY ETF 的年费为 0.0945%。Ondo 保留 其代币报价与标的证券交易价格之间的差额;它未公布固定价差。Binance 列出 bStocks 的佣金、托管、管理以及股票转代币转换费用均为零,交易价差和网络费用在适用时单独收取。Alpaca Securities 为 Ondo 和 bStocks 托管标的证券。Backed 也将 Alpaca 列为 SPYx 的托管人之一。

持有人地址增长 59 倍,而价值增长 7.6 倍

在包装股票代币中,流通市值除以持有人总数从 2025 年 9 月 30 日的 5,325 美元降至 2026 年 9 月 30 日的 682 美元。持有人数量增长 59 倍,而市值增长 7.6 倍。 持有人数量汇总了不同股票代币资产的地址:一个钱包持有五种不同代币则计为五条记录。截至 9 月 30 日,Ondo 每个计入持仓的市值约为 2,100 美元,而 Robinhood 约为 121 美元,大约是其 17 倍。Ondo 还允许 符合条件的个人和机构在完成入驻后进行铸造和赎回,但受司法管辖区限制。
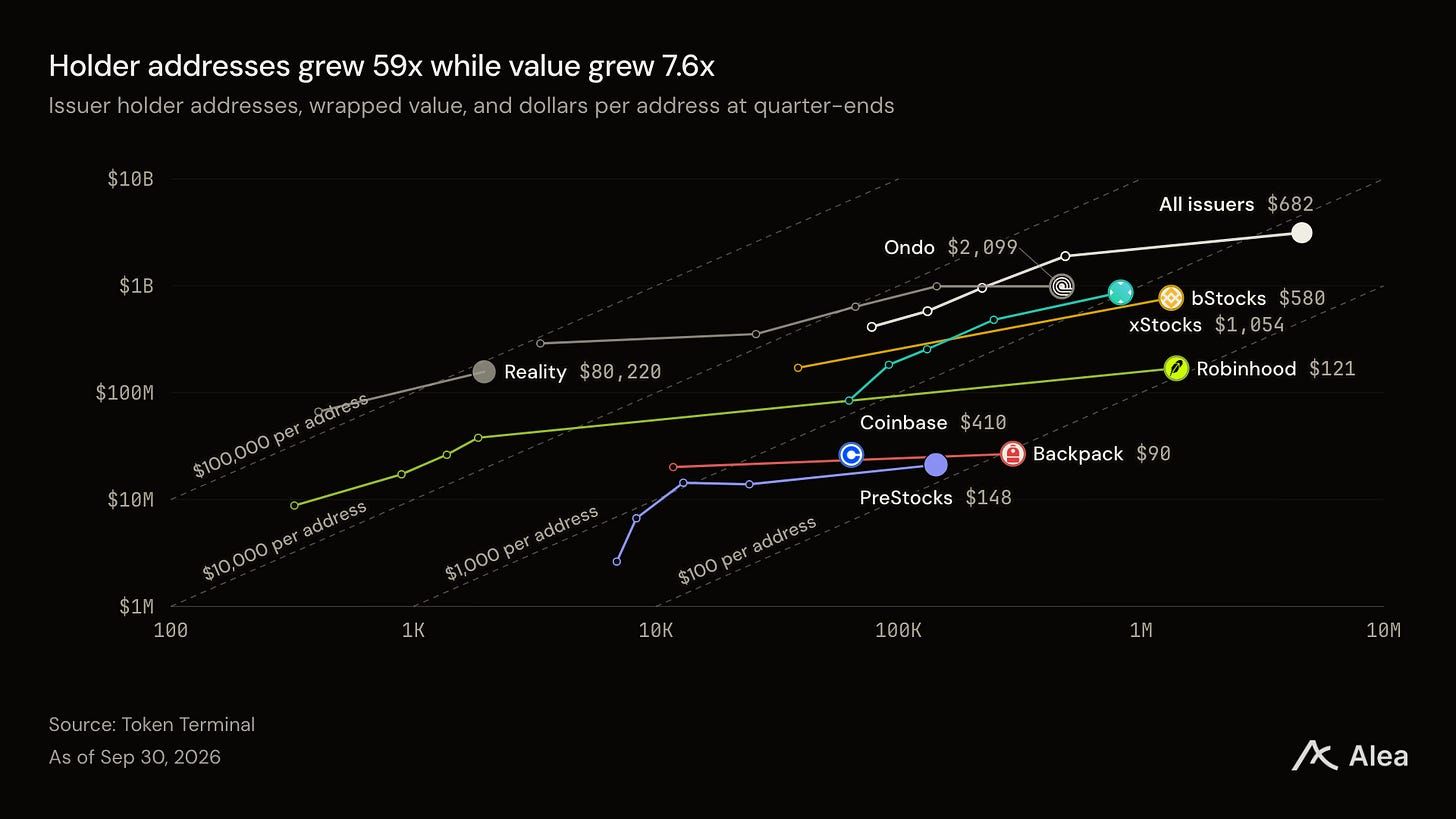
Log-log line chart of holder addresses against value for each wrapped issuer at quarter-ends from Sep 30, 2025 to Sep 30, 2026, ending at $682 per address across all issuers. Token Terminal data.
At Sep 30, 2026, market value per counted holding was about $2,100 for Ondo and $121 for Robinhood. Holder counts sum addresses across distinct stock-token assets.
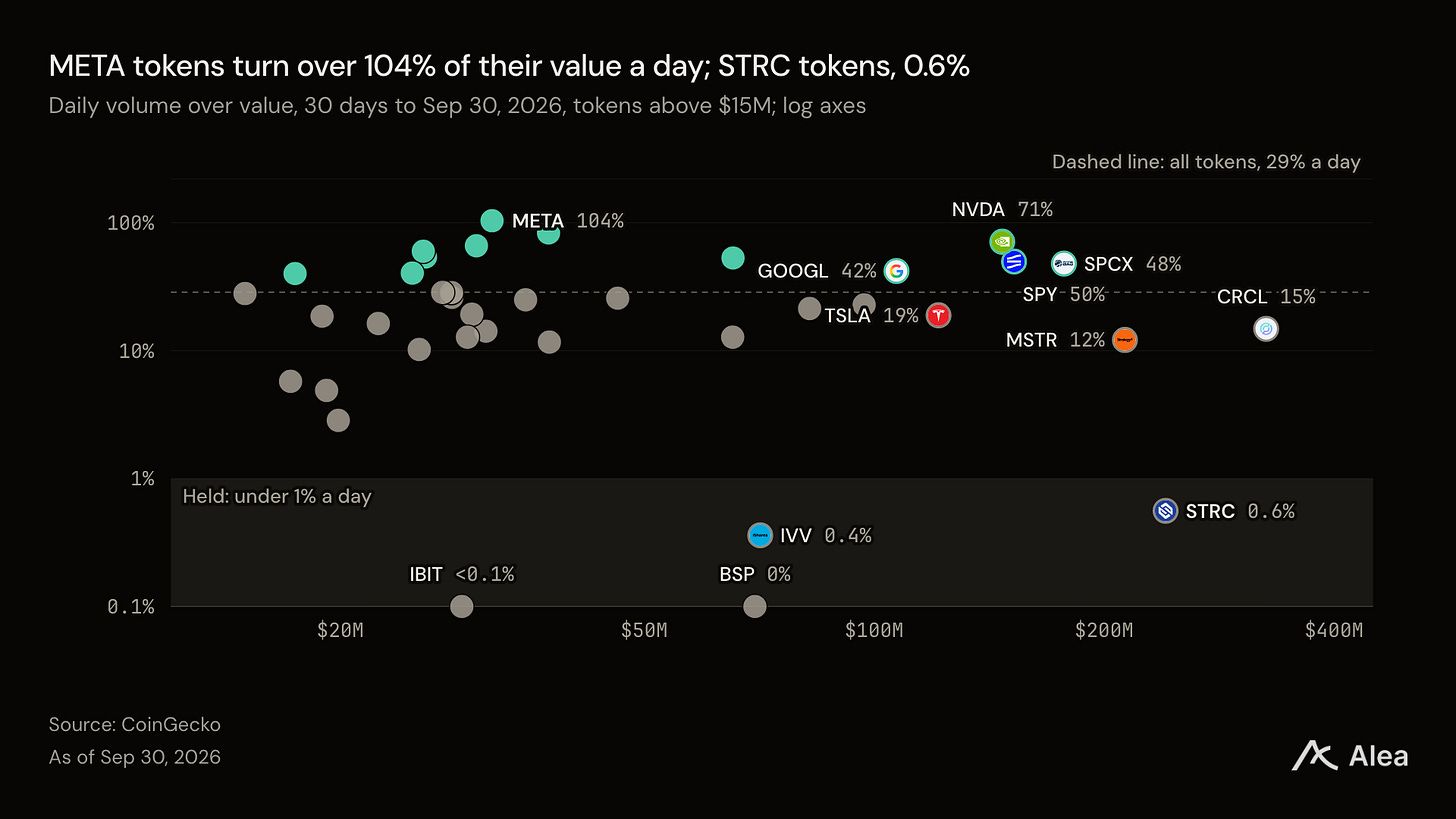
Scatter chart of daily turnover against token value for 38 tokenized stocks above $15M, 30 days to Sep 30, 2026, both log scales, with META at 104% and STRC at 0.6% a day. CoinGecko data.
Four of the 38 largest tokens turned over less than 1% a day: STRC, IVV, IBIT, and Bending Spoons. Turnover is mean daily volume over token value in the 30 days to Sep 30, and exchange volume includes trading that a venue’s points program rewards.

日成交额上升,从一年前占价值的 18% 升至 2026 年 9 月的 29%。部分代币如 META 日成交额达到其价值的 104%,而 Strategy 的 STRC 优先代币仅为 0.6%。

代币收盘价与股票价差 8 个基点

代币交易价格接近其对应股票价格。 第三季度十只大型代币中,中位数代币收盘价与股票价差为 8 个基点,九成代币价差在 24 个基点以内。代币价格汇总了同一股票所有发行人的代币,因此交易量小的代币可能显示旧价格。
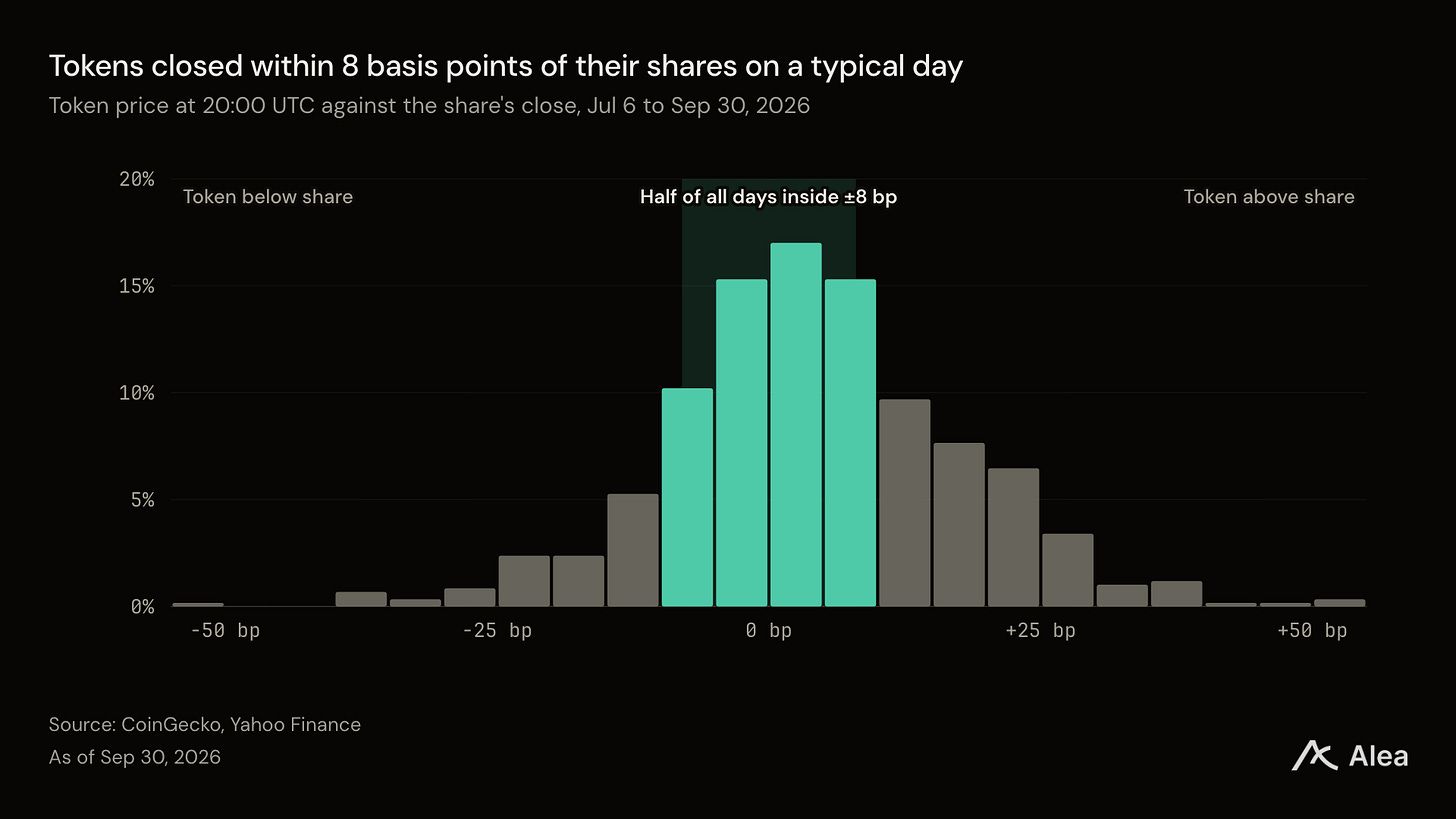
Histogram of the distance between token price and share close for ten tokenized stocks, 588 paired daily observations from Jul 6 to Sep 30, 2026, in 5 basis point bins. CoinGecko and Yahoo Finance data.
Half of all token closes landed within 8 basis points of the share, on either side. Each day compares the token price at 20:00 UTC with the share’s close, for ten names.
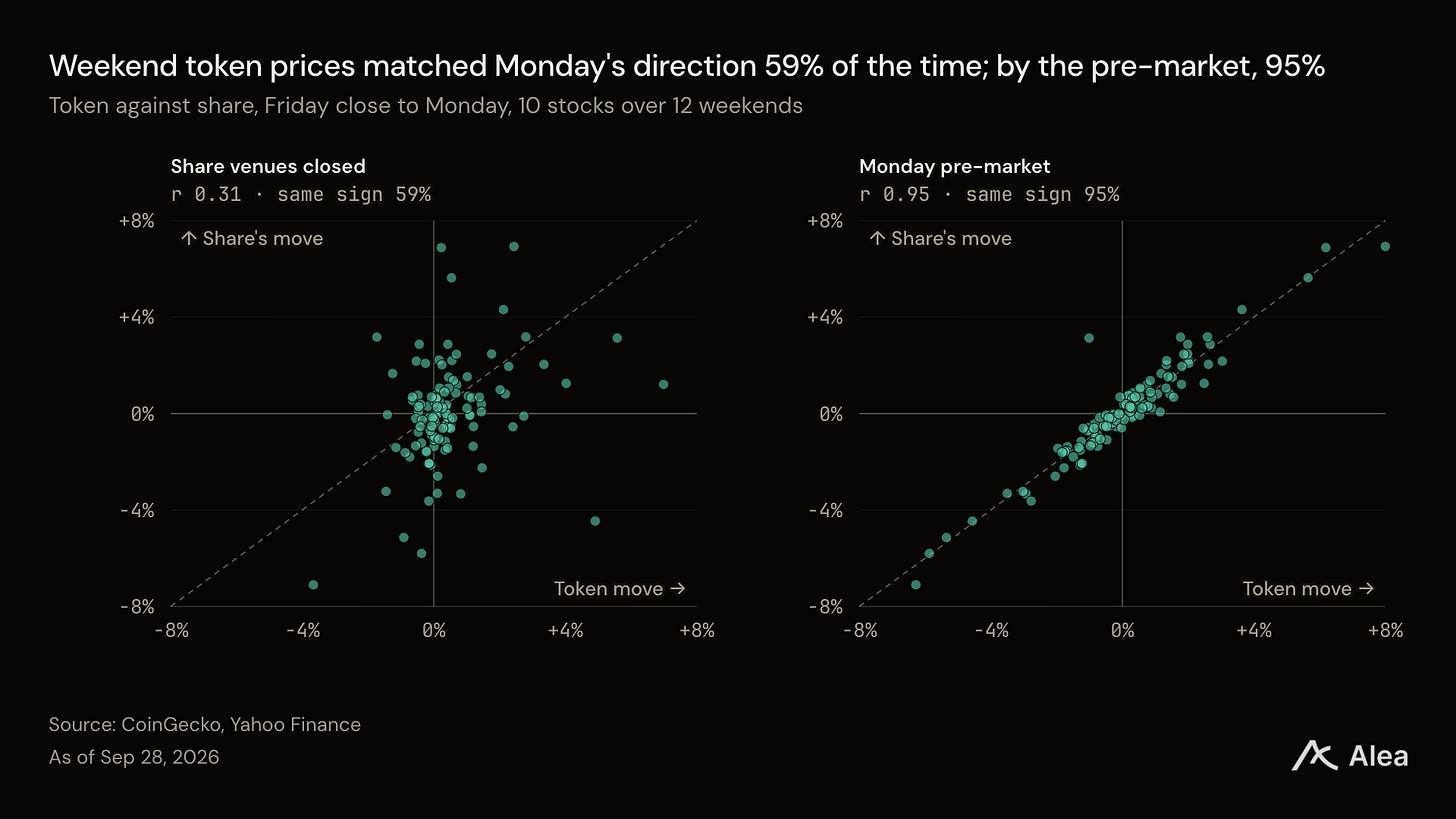
Two scatter charts of token move against share move for ten tokenized stocks over 12 weekends, Jul 10 to Sep 28, 2026: correlation 0.31 over the closed weekend and 0.95 by the Monday pre-market. CoinGecko and Yahoo Finance data.
Weekend token moves matched the direction of Monday’s open more often than not, and the Monday pre-market matched almost every time. The closed window runs from Saturday 00:00 to Sunday 23:00 UTC, and the pre-market read is Monday 13:00 UTC.
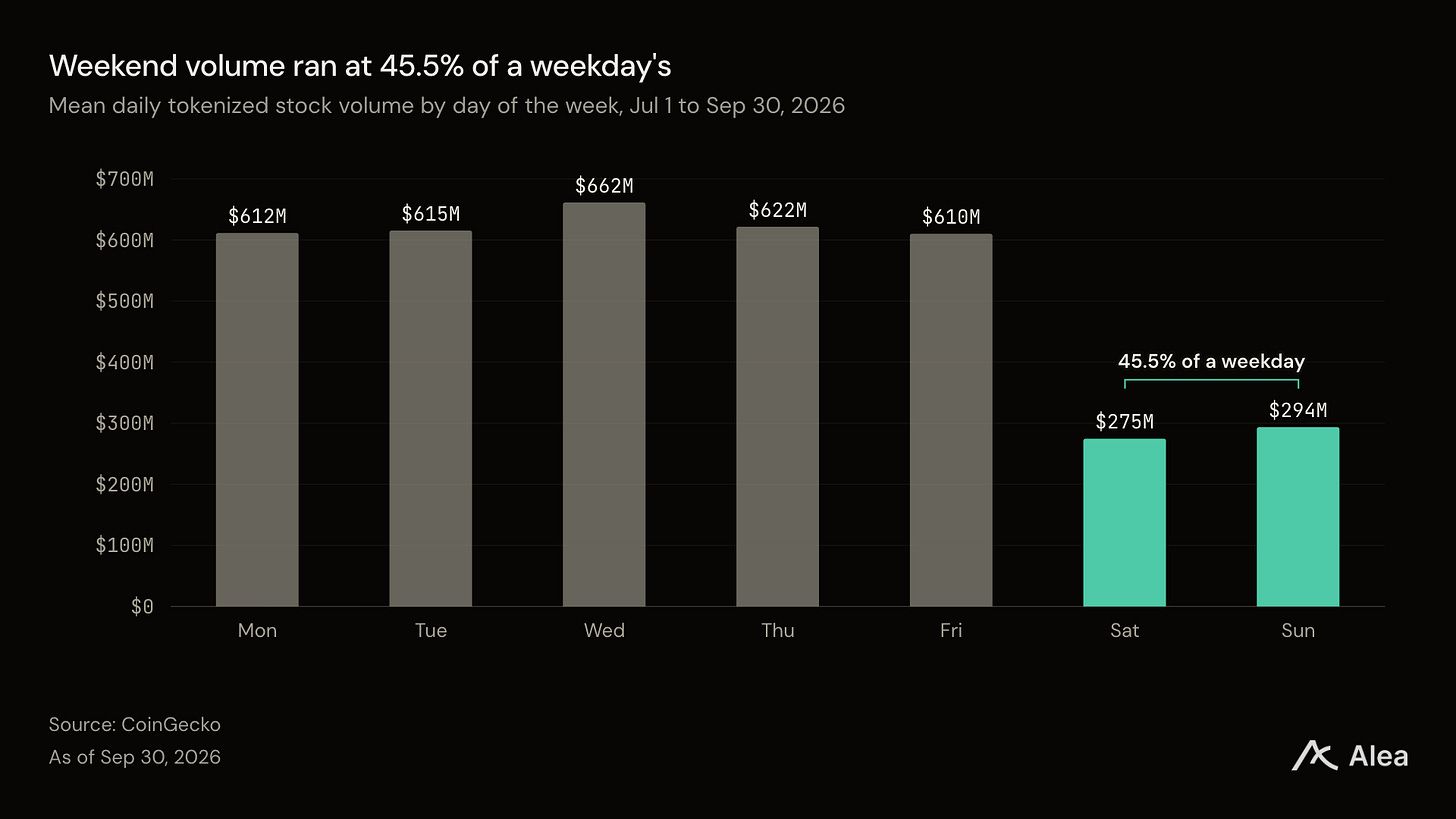
Bar chart of mean daily tokenized stock volume by day of the week, Jul 1 to Sep 30, 2026: about $610M to $660M on weekdays and $275M and $294M on Saturday and Sunday. CoinGecko data.
Saturday and Sunday each carried close to half a weekday’s volume, with no share venue open. Daily means use 13 to 14 observations for each day of the week, in UTC, from CoinGecko.

这些代币还在所有股票交易场所休市时进行交易,同时也暴露了流动性不足和流动性碎片化问题。第三季度每个周六和周日的交易量约为工作日的 45%。在这些休市时段,代币走势与周一开盘方向一致的概率为 59%。到周一盘前,每小时价格显示 95% 的匹配度。该样本仅包含 12 个周末的十只大型股票,且这些股票走势往往一致。

XYZ 权益永续合约成交量为现货的 1.8 倍

Hyperliquid 的 XYZ 市场权益永续合约 2026 年 9 月日均成交 14.3 亿美元,而代币化股票为 8.08 亿美元。两种产品提供不同的敞口。 永续合约以美元结算且不持有股票,而代币是对托管股票的索取权。代币成交量 9 月环比增长 76%,该比率结束 当月时低于 7 月的峰值 9.6 倍。
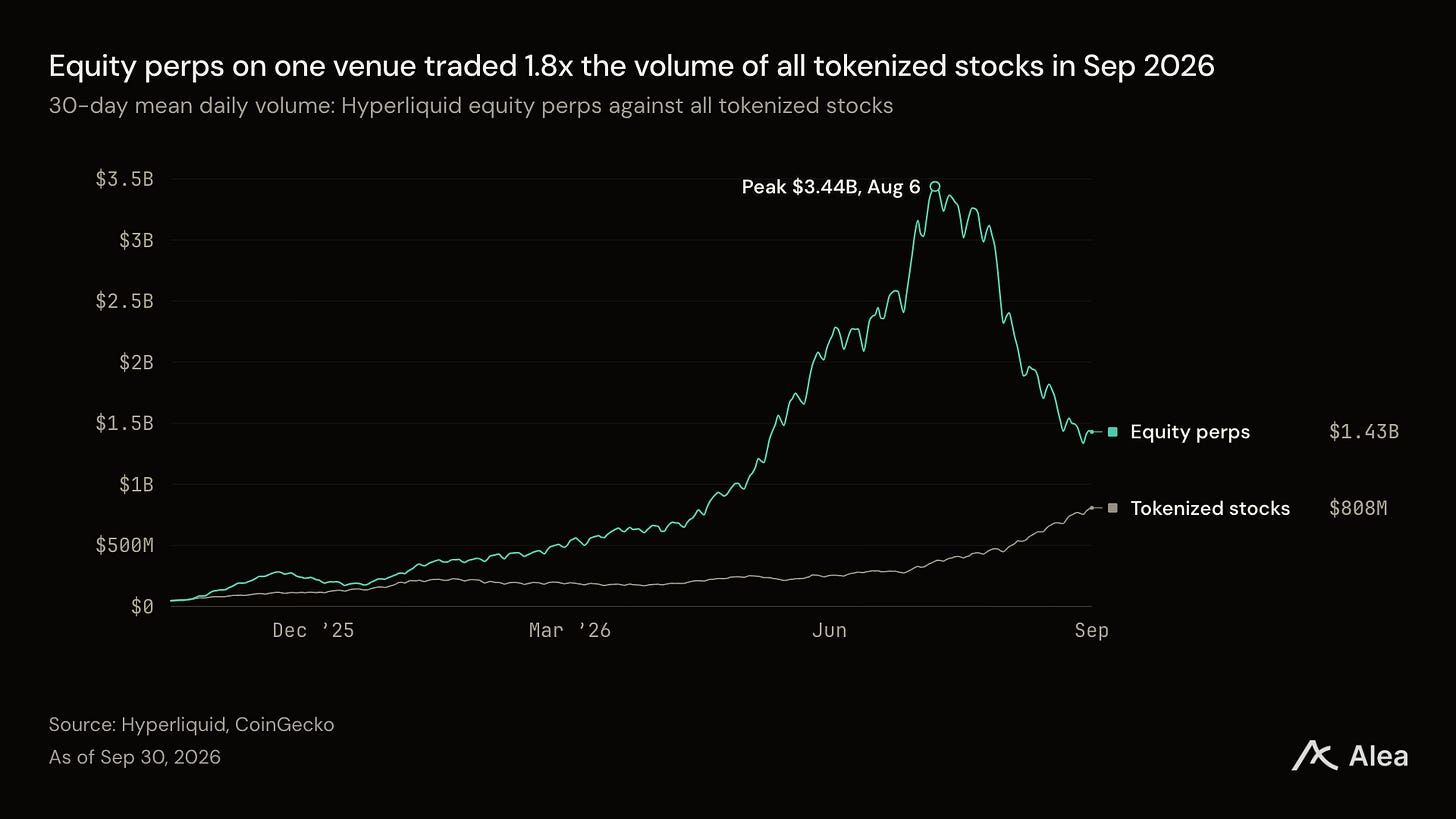
Line chart of 30-day mean daily volume to Sep 30, 2026: equity perps on Hyperliquid peak at $3.44B in August and end at $1.43B, against $808M for tokenized stocks. Hyperliquid and CoinGecko data.
Perp volume peaked on Aug 6 and fell by more than half by Sep 30, while token volume kept rising. Both lines are 30-day means of daily volume.

SEC 在原有市场旁开设第二个市场

SEC 于 9 月 17 日宣布 豁免令。该令允许新场所交易代币化美国股票至 2031 年 9 月 17 日,且仅接受附带股票投票权和分红权的代币。离岸包装股票不附带投票权且再投资分红,因此仍留在离岸市场。每个场所须在开市前 30 天发布通知,最早开市日期为 2026 年 10 月 17 日。

Ondo 已同时发行两种代币。 2026 年 7 月 2 日,Ondo 推出 美国代币,标的为贝莱德标普 500 ETF 和美光,由其自有过户代理发行。持有人享有美国经纪账户的股东权利,包括通过 Broadridge 进行代理投票。
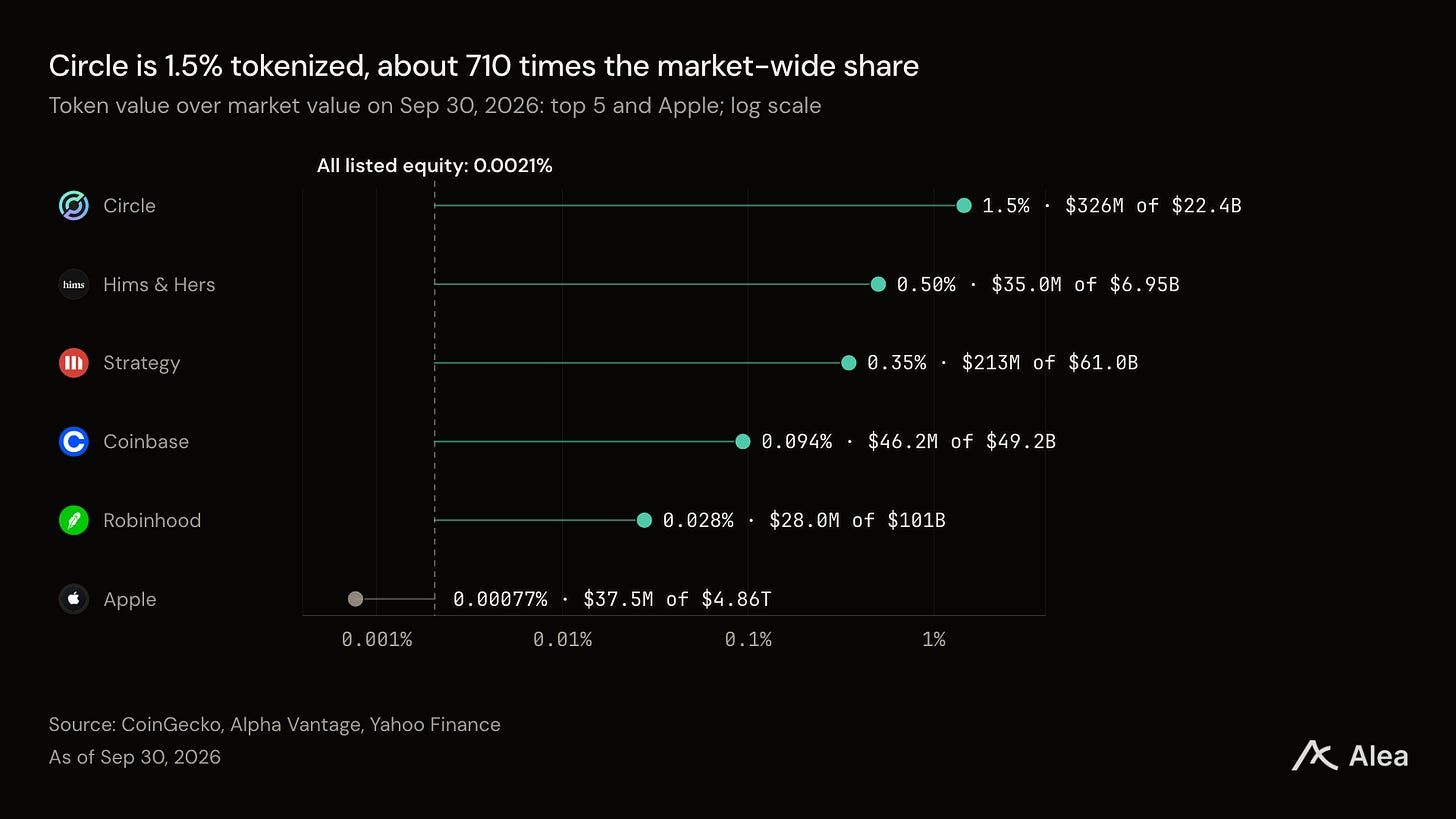
Dot chart of token value as a share of company value on Sep 30, 2026, log scale: Circle 1.5% ($326M), Hims & Hers 0.50%, Strategy 0.35%, Coinbase 0.094%, Robinhood 0.028%, and Apple 0.00077% ($37.5M), against 0.0021% for all listed equity. CoinGecko, Alpha Vantage, and Yahoo Finance data.
Three of the four most tokenized companies are crypto-linked, and Apple’s tokenized share is under a thousandth of Circle’s.

两个市场与上市股票相比仍很小。股票和 ETF 代币仅占 152 万亿美元上市股票市值的 0.0021%,该市场的每 0.1% 即为 1,520 亿美元,约为包装市场规模的 50 倍。Circle 的代币占其公司价值的 1.5%,约为全市场份额的 710 倍。

达到 640 亿美元需满足的条件

保守估计,包装股票到 2030 年 12 月可达 636 亿美元,较 2026 年 9 月 30 日的 31.4 亿美元有所增长。该预测假设代币净发行年增速为 50%,标的股票价格年涨幅为 5%。
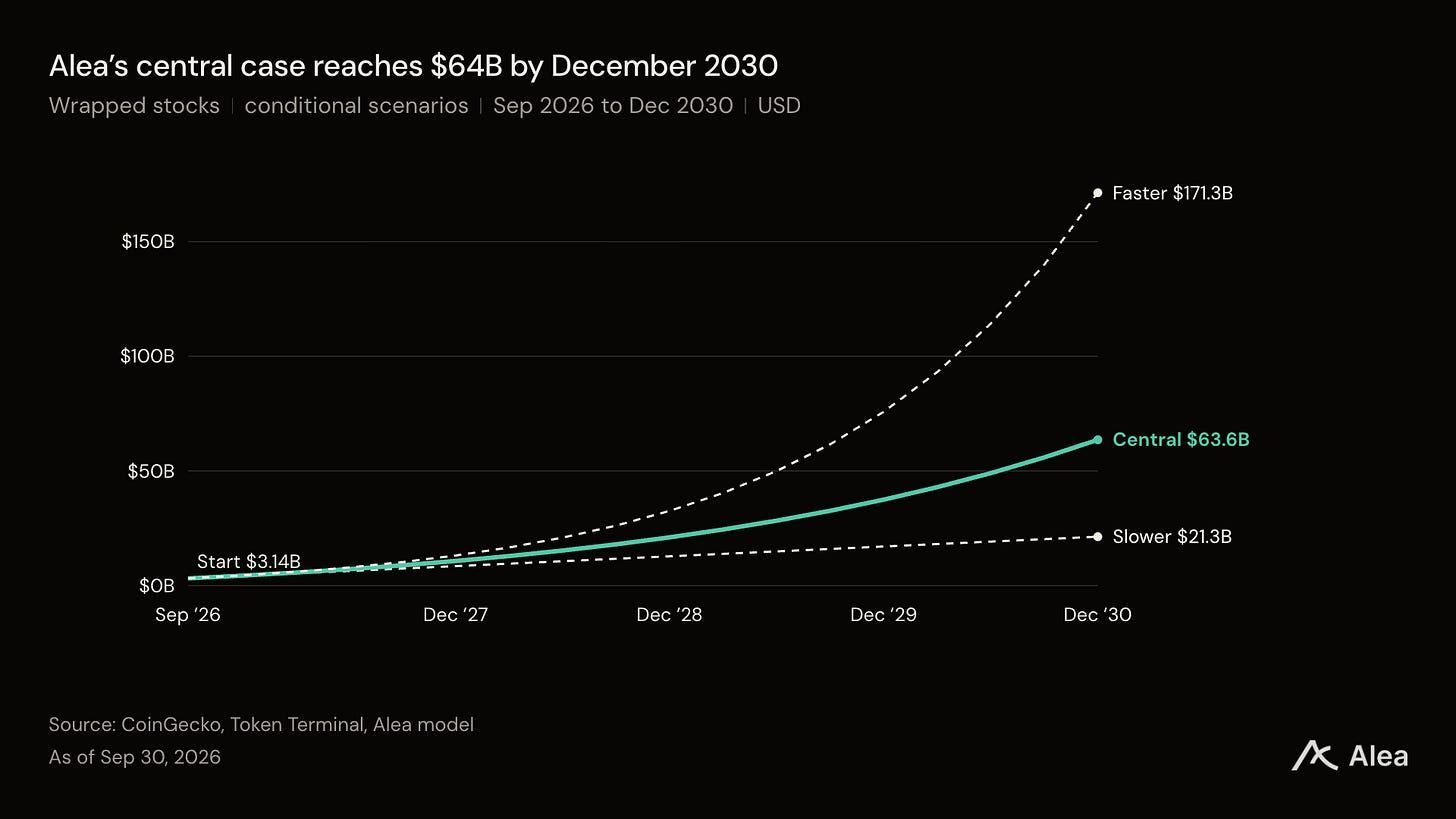
Wrapped-stock conditional paths from $3.14B on September 30, 2026 to December 31, 2030: slower $21.3B, central $63.6B, faster $171.3B. Alea model using CoinGecko and Token Terminal data.
Conditional wrapped-stock scenarios from September 30, 2026 to December 31, 2030. The paths carry no probability weights.

初始发行速度为每年 42.8 亿美元,根据最近两个季度估算得出。代币数量由各资产流通价值除以同期价格推算,并根据检测到的股票拆分进行调整,再按 2026 年 9 月价格估值。此方法将代币单位变化与股价变化分离,而无需衡量现金认购。
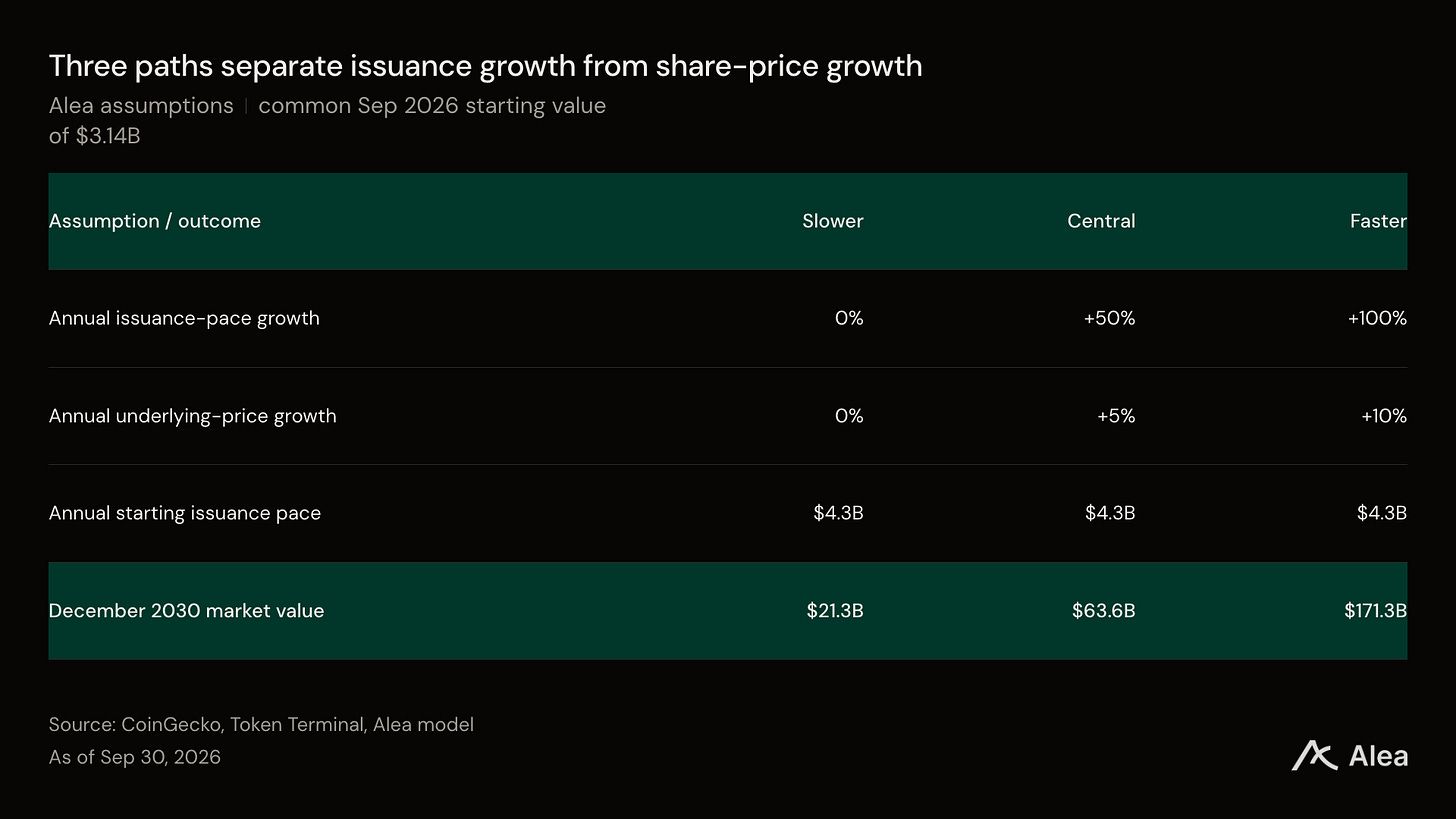
Alea scenario assumptions: annual issuance-pace growth of 0%, 50%, or 100%, with annual underlying-price growth of 0%, 5%, or 10%. All start at $3.14B and $4.28B annual net issuance; 2030 values are $21.3B, $63.6B, and $171.3B.
Each scenario starts at $3.14B and uses the same estimated $4.28B annual net issuance pace. Growth assumptions apply separately to issuance and underlying prices.

较慢情景下,发行速度和价格均保持不变,达到 213 亿美元。较快情景下,发行速度每年翻倍且价格年涨幅 10%,达到 1,713 亿美元。基准情景假设分销持续扩张,但故意不延续最新增速。
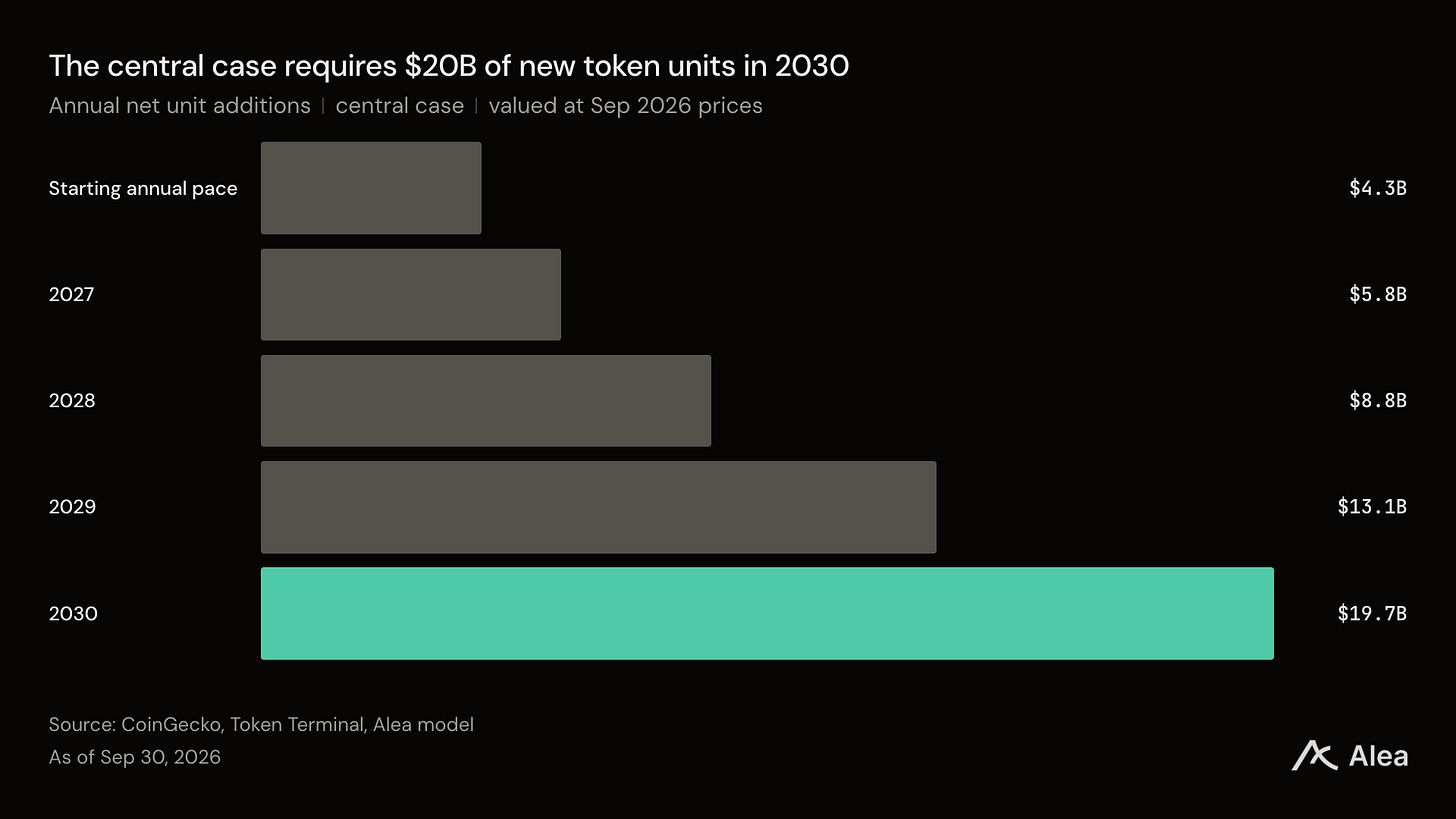
Central-case annual net token additions valued at September 2026 prices: starting annual pace $4.3B; 2027 $5.8B; 2028 $8.8B; 2029 $13.1B; 2030 $19.7B.
Central-case annual net additions rise from $5.8B in 2027 to $19.7B in 2030, valued at September 2026 prices. These amounts describe token units rather than cash subscriptions.

基准情景要求 2027 年新增净代币单位 58 亿美元、2030 年新增 197 亿美元(按 2026 年 9 月价格计算)。在 5% 年价格增长下,发行速度不变将产生 262 亿美元。

发行假设主导预测结果

在 5% 年价格增长下,将发行速度增速从 50% 降至 25% 会使 2030 年结果从 636 亿美元降至 412 亿美元。保持发行增速 50% 不变,价格零增长将产生 517 亿美元,价格年增长 10% 将产生 775 亿美元。所选区间解释了为何分销和持续发行比乐观的股票市场假设更值得关注。使用全年估算发行量而非最近两个季度会将基准情景降至 422 亿美元;仅使用最近一个季度则会升至 778 亿美元。
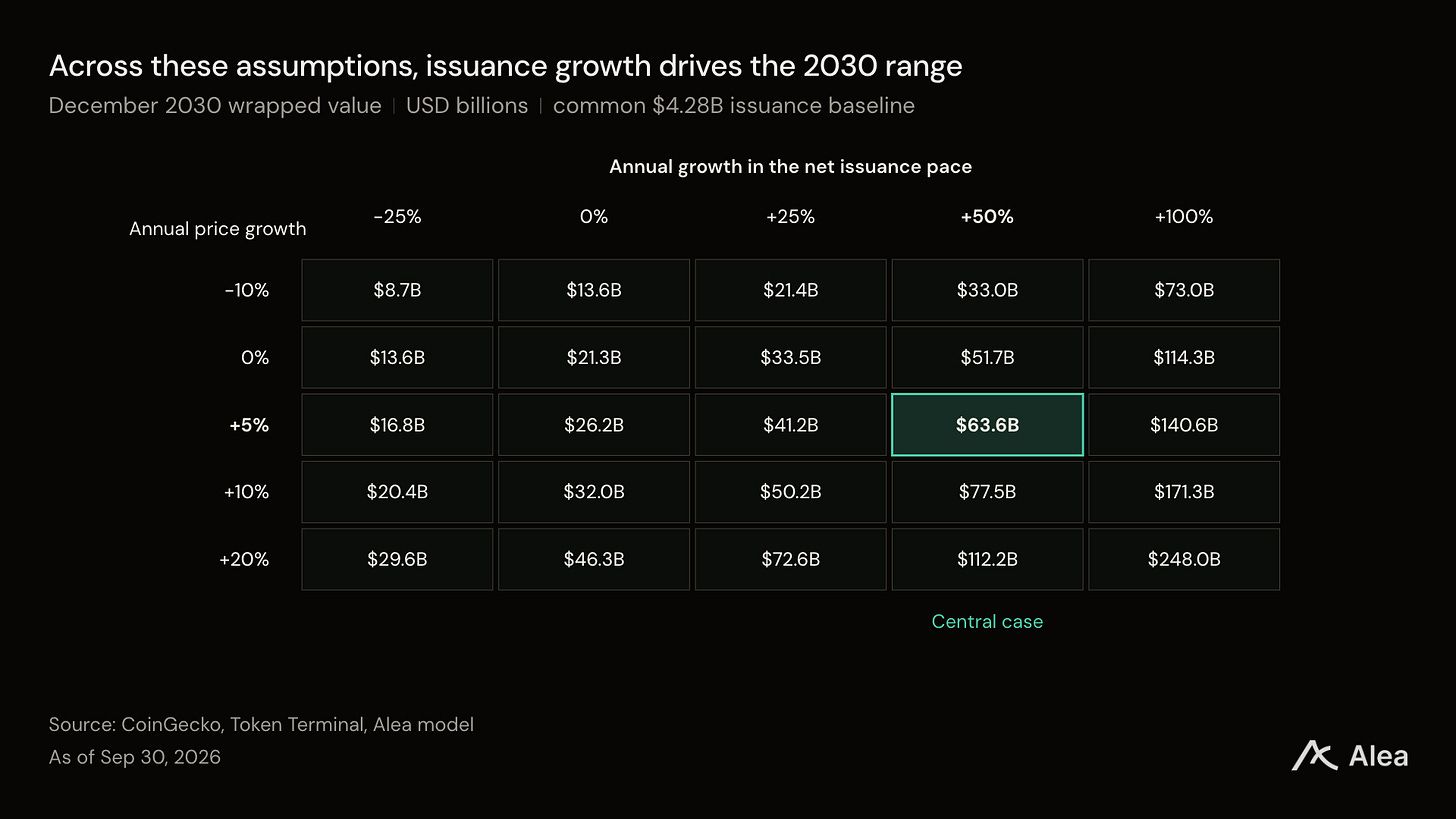
December 2030 wrapped-stock value sensitivity matrix. Columns vary annual net issuance-pace growth from minus 25% to plus 100%; rows vary annual underlying-price growth from minus 10% to plus 20%. The central plus 50% issuance and plus 5% price cell is $63.6B.
December 2030 value across alternative issuance and price assumptions. The highlighted cell is Alea’s central case; the cells have no assigned probabilities.

同时,2027 年路径要求每季度新增约 12 亿至 17 亿美元(按 2026 年 9 月价格计算)。这些修订阈值属于编辑判断。新场所的重要性在于其能否在上市周之后维持发行。

公司发行的股份保持独立。截至9月30日,其总额为4.76亿美元;其股东权利和分配与包装产品不同,且短期记录不支持应用相同的发行假设。相对于1.52万亿美元的上市股权参考,包装后的中心情况仍仅约为0.042%。

重要链接

Alea Research logo centered between two light blue horizontal rules.

Alea Research覆盖代币化股票及上市和交易这些产品的场所。

  • 研究报告。深度研究与蓝图解析协议及其经济模型。论文与备忘录探讨投资案例与催化剂。基准比较绩效,观点评估具体发展。

  • 每周脉搏。阅读宏观与主要流动市场的每周评估。

  • 协议数据室。在一处研究每个协议,提供历史比较分析与可用新闻及治理动态情报。

  • 播客摘要与峰会摘要。阅读行业对话与活动的总结。通过播客摘要查找Alea的节目及其剧集。

  • 治理追踪器。跟踪跨协议的提案与投票活动。

对于准备机构对话的协议团队,与Alea讨论贵协议的研究。

探索Alea Research