Onchain perpetual futures scaled by replicating CEX infrastructure: order books, leverage, and fast execution. Options stayed concentrated on centralized exchanges because the product is structurally harder to decentralize: liquidity fragments across thousands of strike and expiry combinations, market makers need to continuously price volatility, and capital efficiency requires portfolio margin that isolated collateral can't provide.
Derive, rebuilt from the former Lyra Finance, operates an OP Stack Layer 2 with a CLOB, portfolio margin, and a fee-buyback model.
In this edition, we look at what Derive rebuilt and how far the Deribit volume gap has closed.

Why Options Require Different Infrastructure
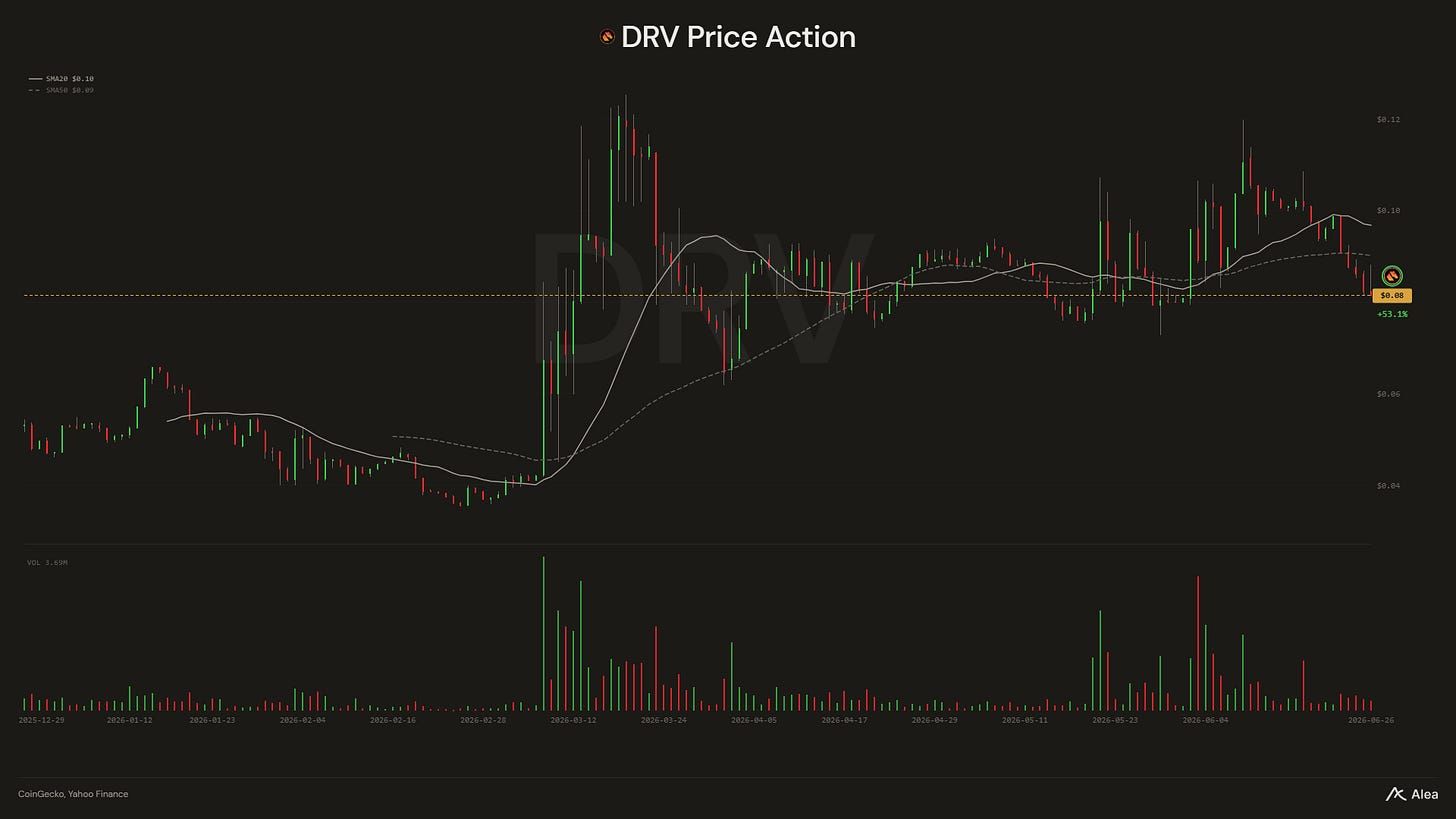
Derive is a live onchain derivatives venue on an OP Stack Layer 2, covering spot, perpetuals, options, and portfolio margin in a single trading engine. It launched as Lyra Finance and rebuilt its core architecture after its AMM model produced wide spreads and thin books. DRV is the governance token, with 35% of protocol revenue routed to weekly buybacks.
An option’s price updates constantly as spot moves, time decays, and implied volatility shifts. A market maker quoting options needs to refresh bids and asks across every live strike and expiry with each market move.
An AMM prices by formula and can’t do this, which is why early onchain options venues either had wide spreads, thin books, or required subsidized liquidity that evaporated when incentives ran out. A CLOB with professional market makers can continuously reprice with proper execution speeds on L2s that makes this viable.
Portfolio Margin and the Protocol Revenue Model
Perpetuals work with isolated margin because each position’s directional risk is bounded. Options positions create complex cross-portfolio exposures: a short call, a long put, and a spot position can partially offset each other’s risks, but isolated margin treats them as independent and charges full collateral for each. Portfolio margin accounts for those offsets, reducing the capital a market maker needs to hold and making tight spreads economically viable at scale.
As volume grows, 35% of protocol fees flow into weekly DRV buybacks, shifting staking rewards from scheduled emissions toward buyback-funded over time. RFQ trading handles larger block trades alongside the order book, and Coinbase’s DRV listing broadened token access beyond the protocol’s existing trading community.
How Far the Deribit Gap Has Closed
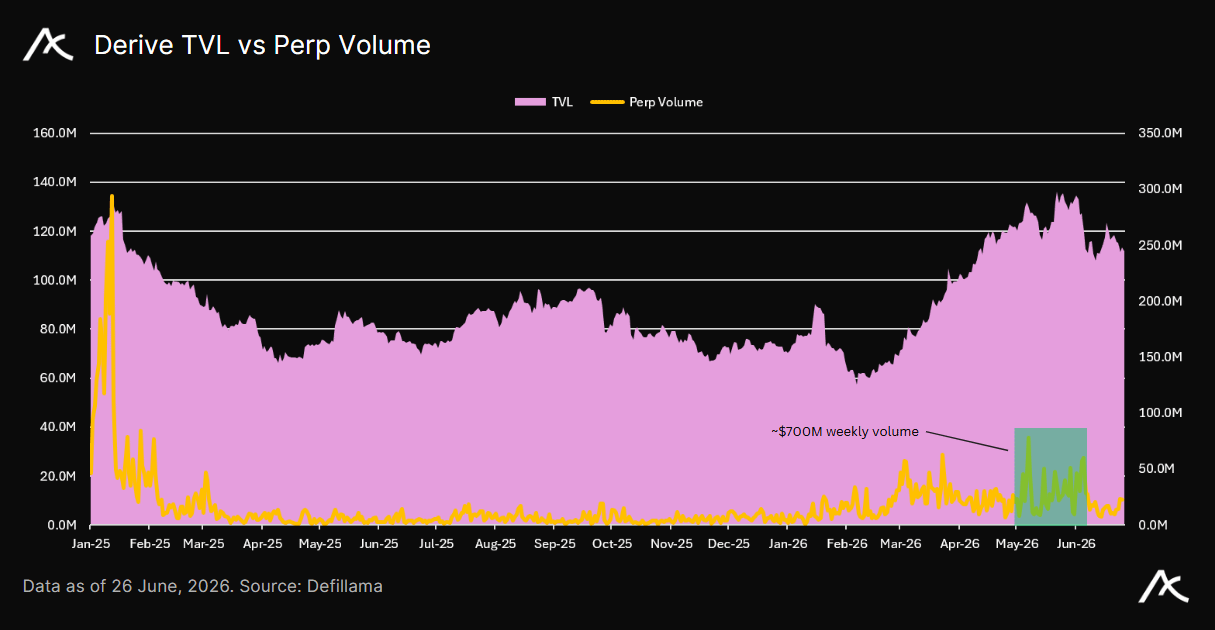
In March 2026, Derive recorded roughly $294M in weekly options volume during elevated volatility, with open interest crossing $1B. By early June, weekly volume had reached $707M. At the March peak, daily options volume ran at roughly 8% of Deribit’s, more than any prior onchain options venue has reached. BTC options account for most activity while ETH and HYPE markets have grown alongside.
Hyperliquid showed that decentralized perp trading could compete with CEXes when the trading experience matched what professional traders expected. Derive is testing that theory with options trading. Deribit’s moat is fast execution, professional market makers, and portfolio margin, and Derive has all three onchain. Deribit’s volume lead remains large, and options liquidity self-reinforces, which means displacement is slow even when the alternative product is competitive.
The volume trajectory from $294M in March to $707M in June is the signal worth tracking ahead of any Deribit share metric. If market maker depth continues building at the CLOB level and open interest holds above $1B through lower-volatility periods rather than only during spikes, the onchain options thesis moves from catching volatility events to providing persistent depth.