跳至内容

Column 买下了大家都在租的银行

2026年10月1日8 min

过去十年的每一位金融科技创始人都在租用银行。William Hockey 买下了一家。他和 Annie Hockey 以约 $50M 的价格购买了加州 Chico 的一家单分支银行,然后花了两年时间让它变得更糟,因为他们正在重写其中的每一块软件。2019 年那家银行很普通。其所有者存入的每 $100 每年产生 $12 的利润,大致相当于任何美国银行的水平。现在它产生 $73,增长 506%。
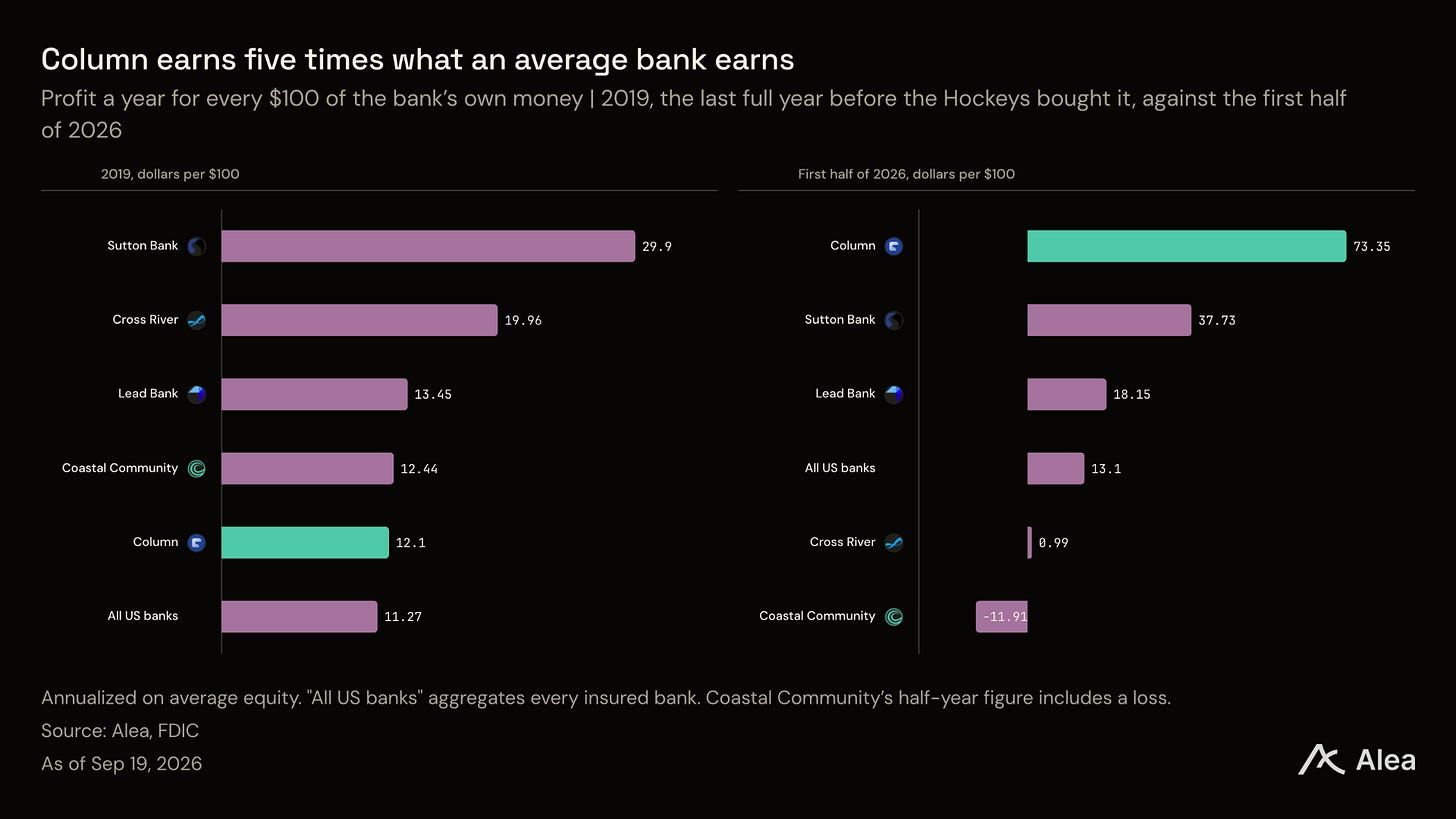
Two ranked bar panels showing profit a year for every $100 of each bank's own money. In 2019 the order is Sutton Bank 29.90, Cross River 19.96, Lead Bank 13.45, Coastal Community 12.44, Column 12.10, and all US banks 11.27. In the first half of 2026 the order is Column 73.35, Sutton Bank 37.73, Lead Bank 18.15, all US banks 13.10, Cross River 0.99, and Coastal Community minus 11.91.
Column and the average American bank were within a dollar of each other in 2019. The gap is now $60.

要点

  • Column 获得政府许可持有存款。它还编写了自己的所有权记录,并自行批准卡支付。几乎没有银行能做到第三点。

  • 拥有这些部分体现在银行的支出上。Column 每赚 1 美元花费 39 美分。Lead Bank 花费 79 美分,两者约 61% 的收入来自费用。

  • 该银行现在从费用中赚取的收入超过贷款。2026 年上半年费用达到 $77.2M,超过 2025 年全年。

  • 持卡人可在数字美元到账的瞬间进行消费,无需先存放在卡公司。

金融科技通常需要租用的部分

持有他人资金需要政府许可。该许可需要数年时间和大量律师费用。监管机构很少将许可授予没有历史的公司,因此金融科技公司会采取更明智的做法。它支付小银行费用以在该银行牌照下持有存款,然后在其上构建应用。

租用牌照只是第一笔账单。一家希望持有资金并在其上发行卡的公司会聘请一系列其他公司。一家银行持有特许权。一家中介记录谁拥有哪些美元。一家卡公司批准每笔支付。还有一家专门处理跨境资金的公司。每家公司都收取费用,且彼此无法查看对方的记录。
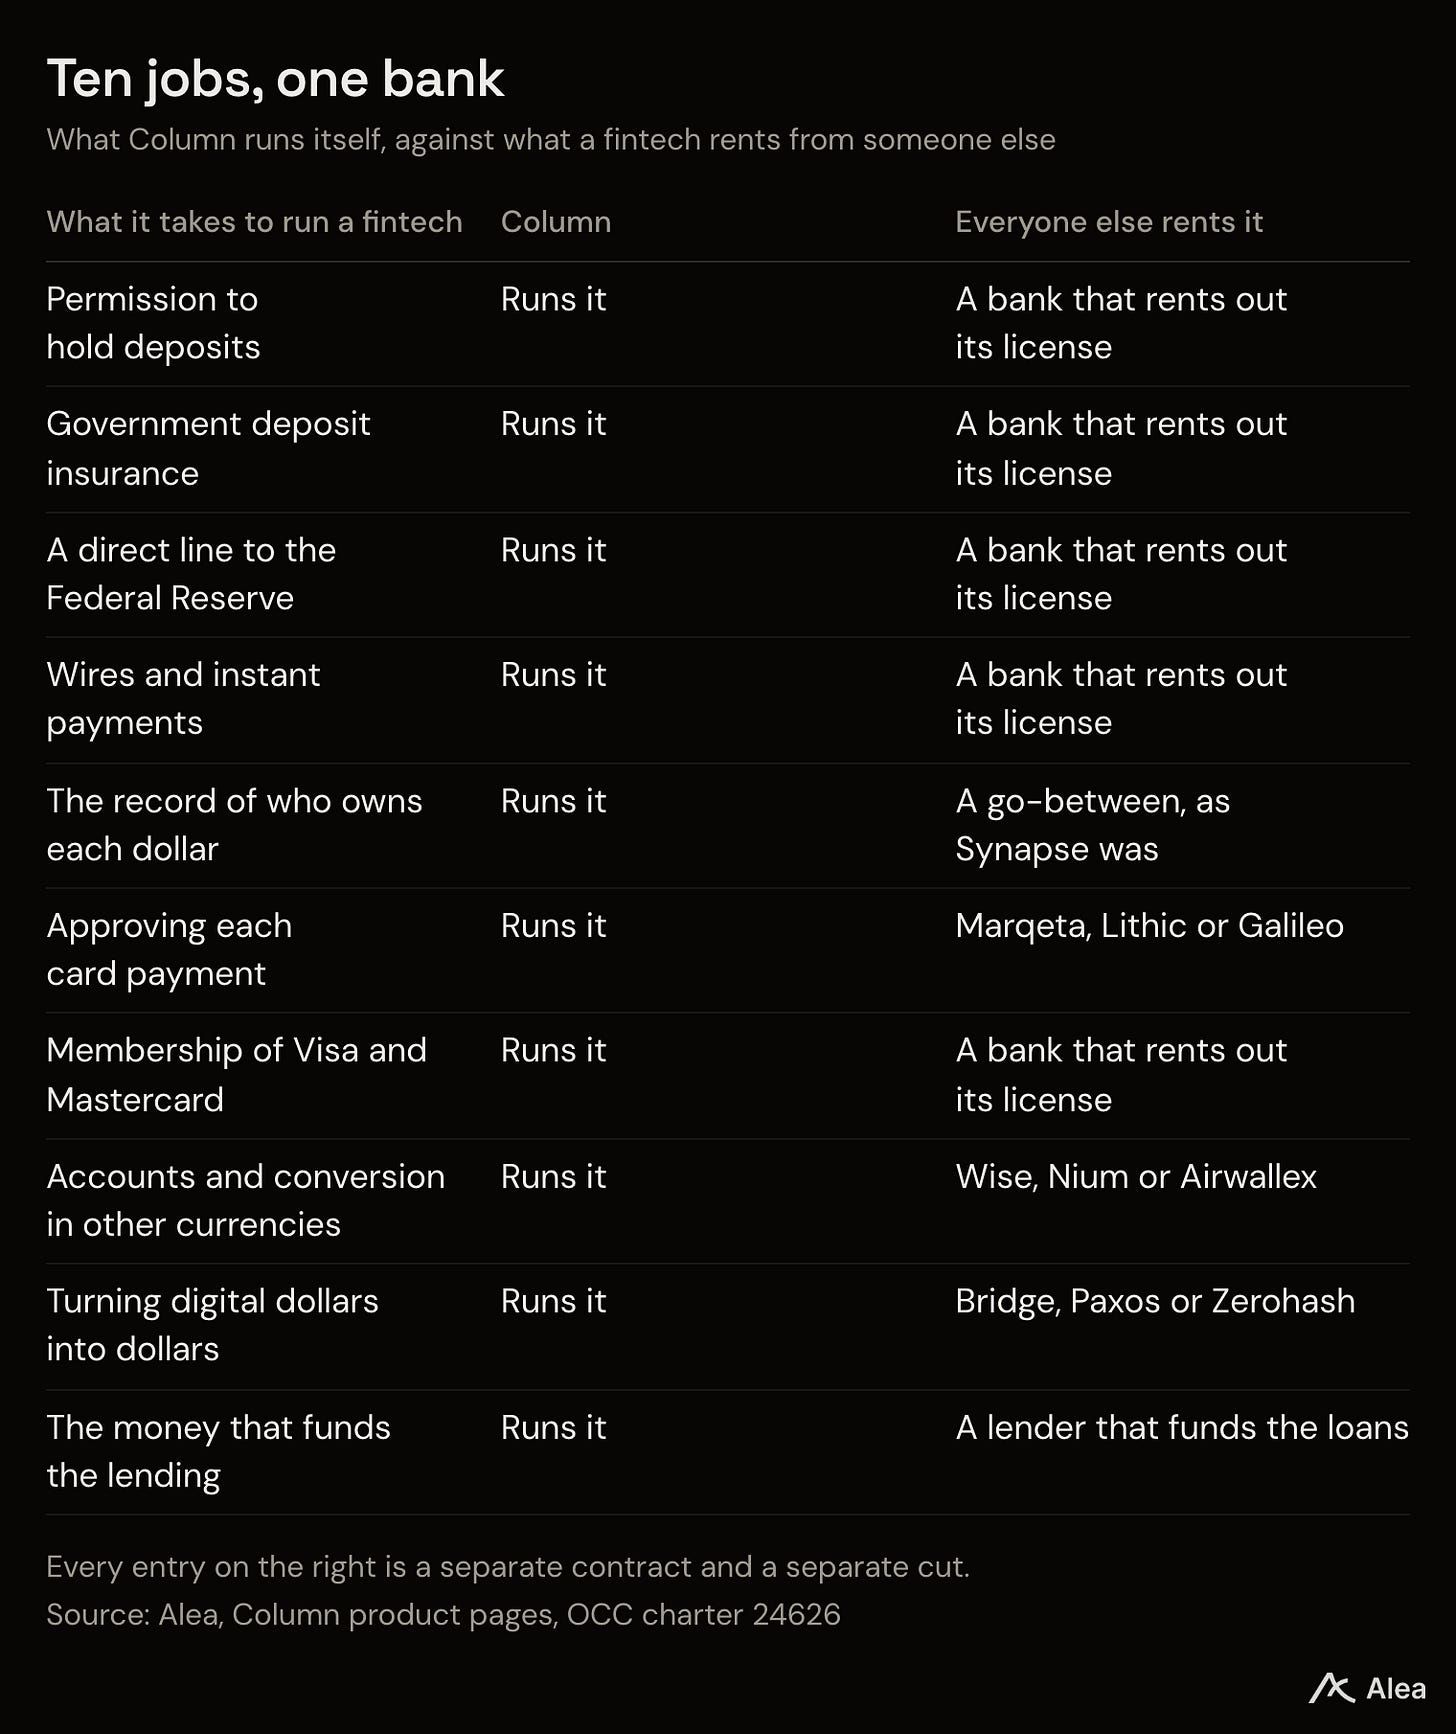
A table of ten jobs a fintech has to cover. Column runs all ten itself. The right column names what a fintech rents instead: a bank that rents out its license for deposits, insurance, a Federal Reserve line, wires and instant payments, and card-network membership; a go-between for the record of who owns each dollar; Marqeta, Lithic or Galileo for approving card payments; Wise, Nium or Airwallex for other currencies; Bridge, Paxos or Zerohash for digital dollars; and a lender to fund the lending.
Column runs all ten itself. The right-hand column is six separate counterparties, each on its own contract.

Column 自行完成所有这些工作。它持有特许权并构建了自己的分类账来追踪所有权。它在 Visa 和 Mastercard 上发行卡,无需其他银行介入。它还运行自己的硬件,直接连接国内的 Federal Reserve 和国外的 Swift。

Hockey 直言:“与拼接银行、协调者、发卡处理器和十几个其他供应商不同,现在你只需要一家银行。”

谁在与 Column 合作

你可以查看客户名单,因为银行必须在合作伙伴的披露中被提及。Brex 披露 Column 持有其企业支票账户。Mercury 声明 其银行业务通过 Choice Financial 和 Column 运行。Slash 确认 Column 为其 Visa 白金卡发卡。Best Egg 披露 其个人贷款来自 Cross River 或 Column。Ramp、Bilt 和 Kapital 在 Column 于 9 月 16 日 推出 时被列为客户。
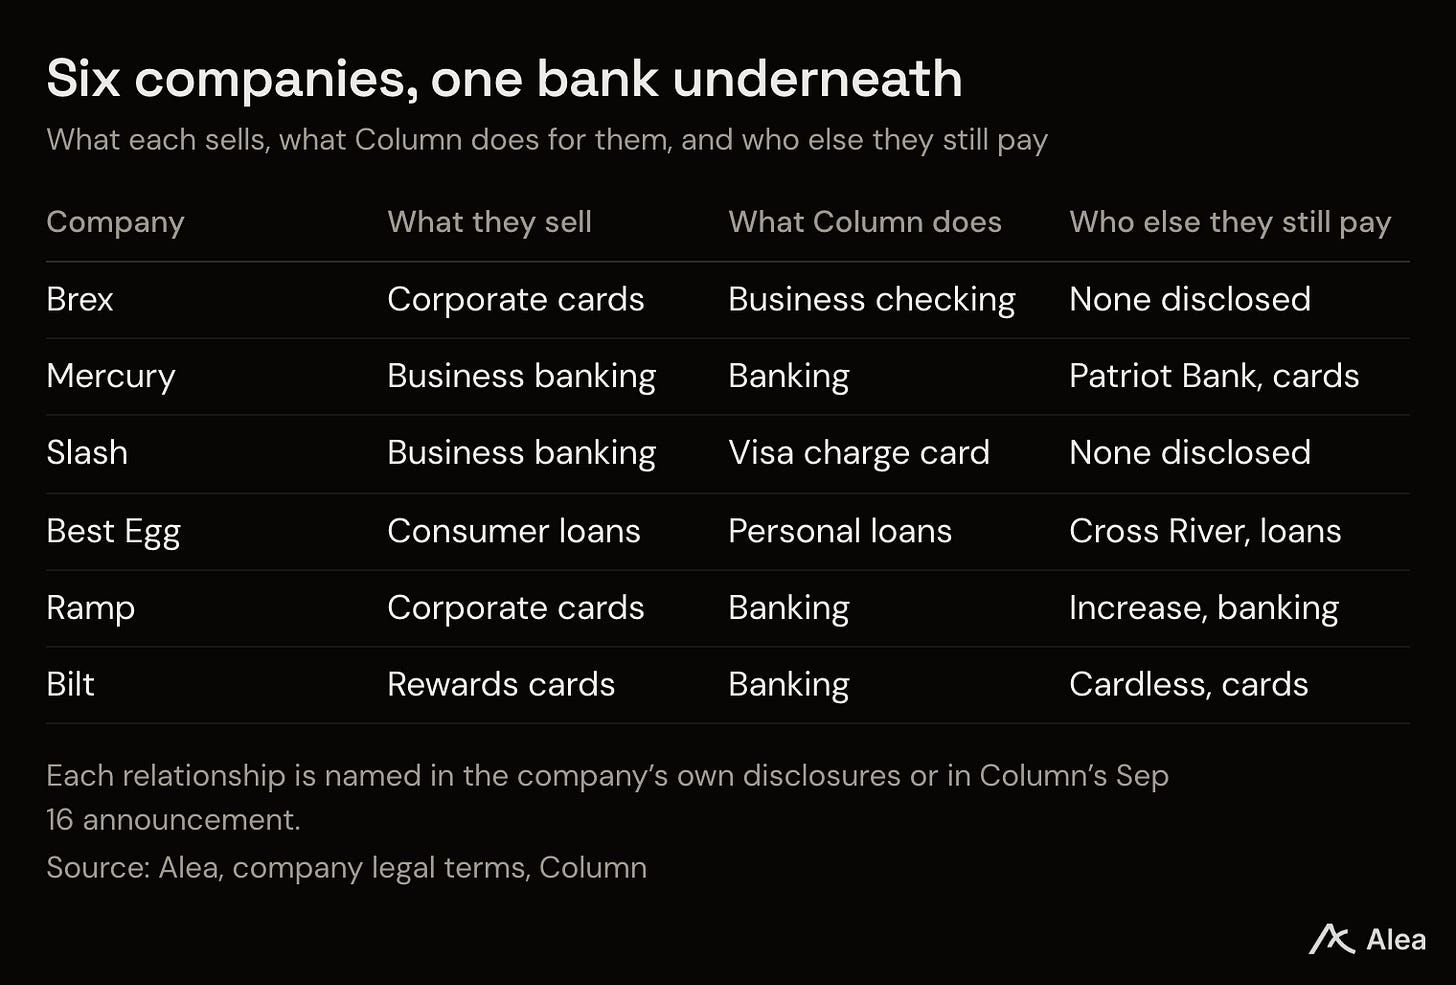
A table of six Column customers. Brex sells corporate cards and uses Column for business checking, with no other provider disclosed. Mercury sells business banking, uses Column for banking, and uses Patriot Bank for cards. Slash sells business banking and uses Column for a Visa charge card. Best Egg sells consumer loans, uses Column for personal loans, and also uses Cross River. Ramp sells corporate cards, uses Column for banking, and also uses Increase. Bilt sells rewards cards, uses Column for banking, and uses Cardless for cards.
All six bank with Column. Four of them still pay someone else for a job Column now sells.

存款 升至 6 月底的 $1.53B,较 2021 年初的 $296M 增长。这是金融科技公司为开展业务存放在银行的资金,会随结算日期波动。该数字在 12 月底降至 $688M,之后六个月内翻了一番多。
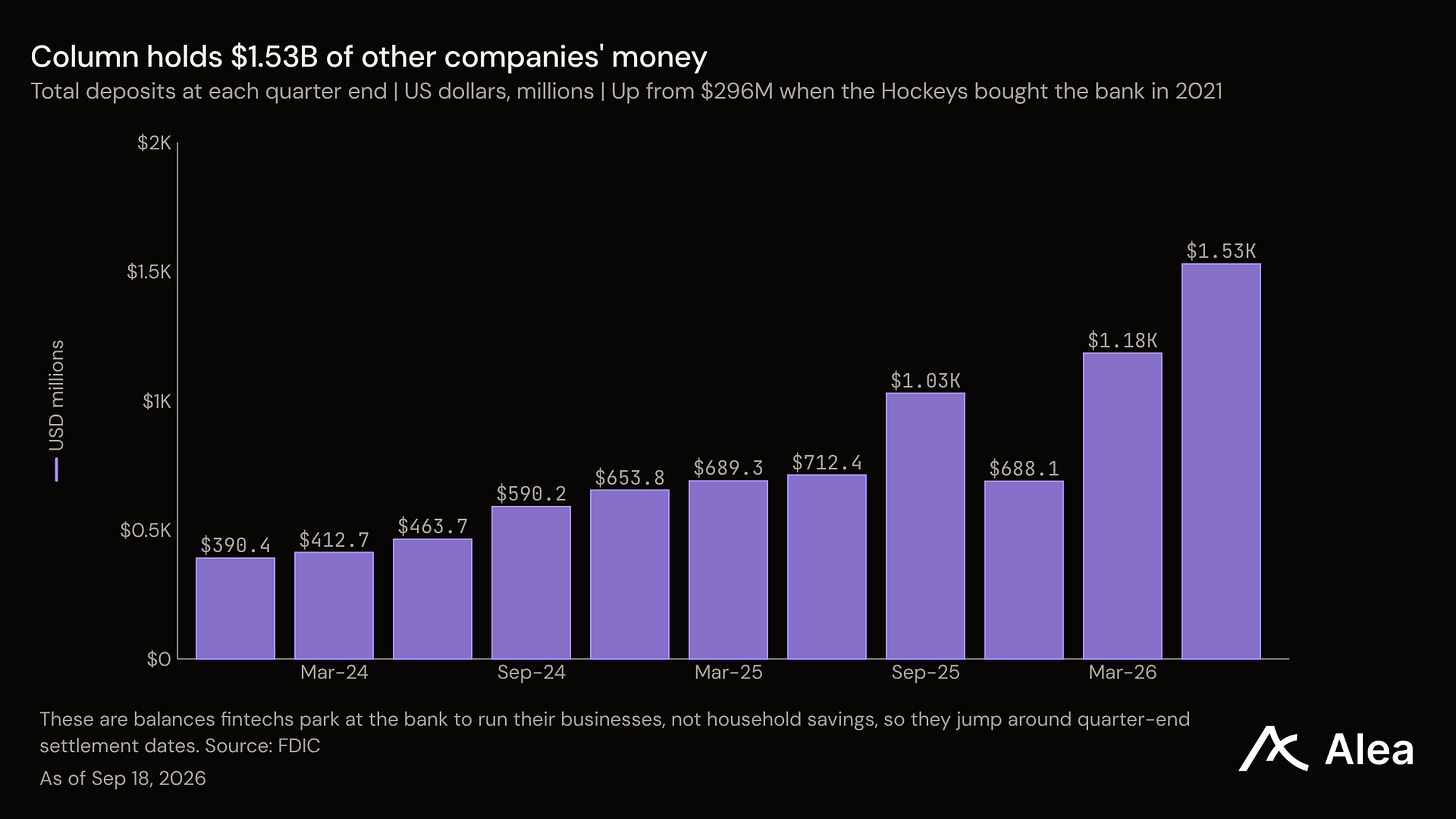
Column's total deposits at each quarter end over the last eleven quarters, in millions of dollars. Deposits climb to $1,029M in the third quarter of 2025, fall to $688M at year end, and reach $1,530M by June 2026.
Deposits reached $1.53B in June. The fall to $688M in December and the doubling that followed is how platform money moves around settlement dates.

为什么你的资金需要以你的名义持有

银行账户上有你的名字,但通过应用持有的资金往往没有。

例如,Synapse 介于金融科技应用与其合作银行之间,将数千名客户的余额汇集到一个大账户中,并在自己的数据库中记录谁拥有哪部分。该数据库出现故障。该公司于 2024 年 4 月 22 日 申请破产,托管人 报告 有 $65M 至 $96M 的客户资金失踪。认为自己持有受保存款的人无法证明哪些美元属于他们。

Column 以相反方式构建账户。当它为平台的客户持有资金时,每位客户在银行自己的账簿中获得一个编号账户。Column 的新外币账户也以客户自己的名义携带账户号码。

银行保留名单,政府检查的对象是银行(Column 从未受到监管机构的执法行动)。

自行编写银行的运行成本

重写银行在进行时成本高昂,之后则变得便宜。银行将其记录保存在少数供应商出售的软件上,每次更改都需要工单和费用。Hockey 的团队抛弃了这些并自行编写。两年内,银行在仍像小型贷款机构一样赚取收入的同时支付工程师费用。这就是 2022 年数字的全部故事:119.64%,即每 $1.00 收入对应 $1.20 的支出。

现在看 Lead Bank,其 61.9% 的收入来自费用,几乎与 Column 的 60.8% 完全相同。两家银行的赚钱方式相同。但 Lead Bank 每 $100 自有资金每年赚 $18,而 Column 为 $73。
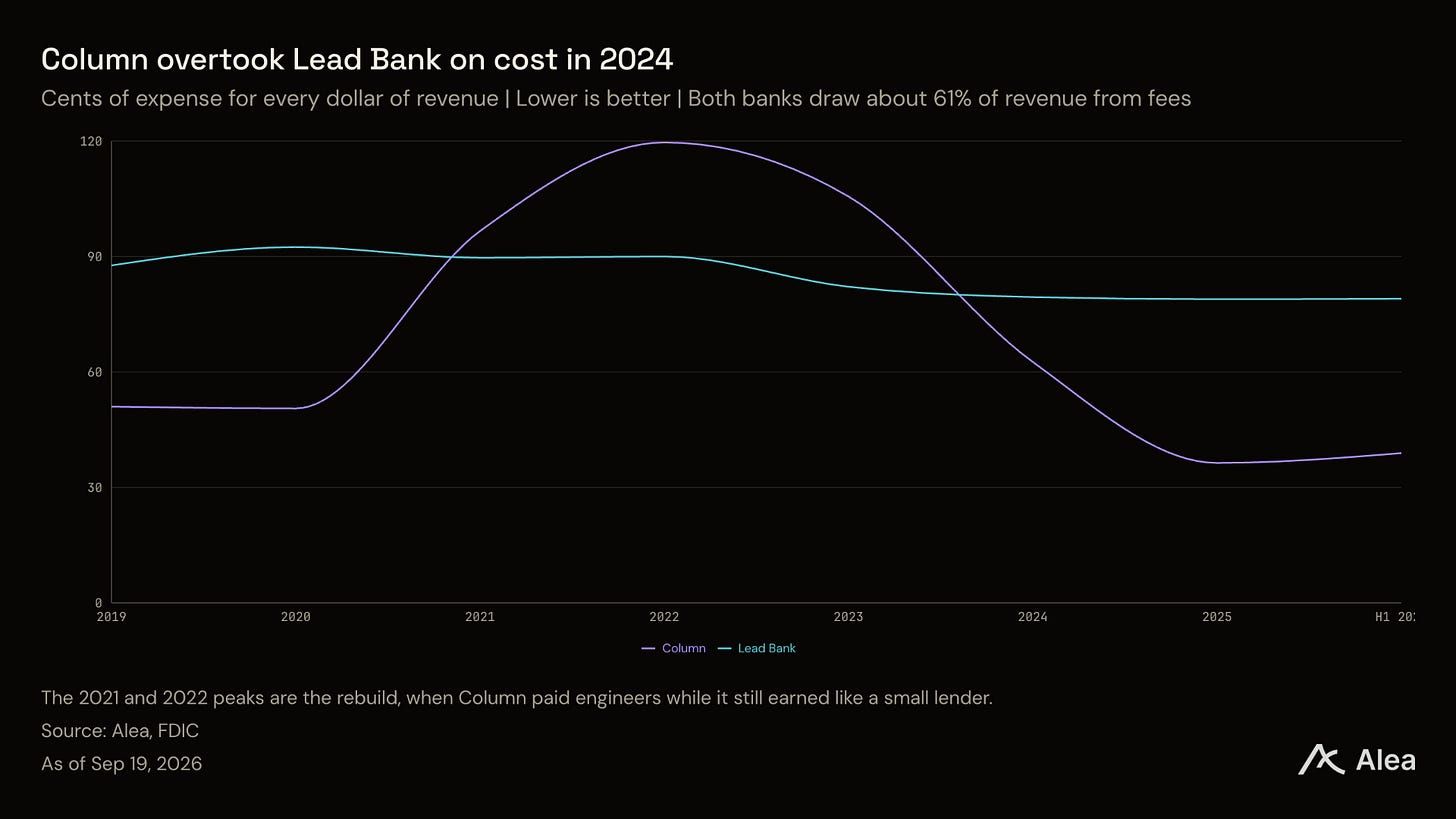
Cents of expense for every dollar of revenue, from 2019 to the first half of 2026. Column starts at 51.00, rises to 119.64 in 2022 while it rebuilds its software, then falls to 36.36 in 2025 and 38.91 in the first half of 2026. Lead Bank stays between 78.90 and 92.46 throughout.
Column's cost line crossed below Lead Bank's in 2024 and has stayed there. The 2022 peak is what the rebuild cost.

9 月 16 日发布的内容

稳定币 在同一账簿上为银行账户提供数字美元地址。Column 与 Slash 和 Brex 一起 推出 了该功能,在 Solana 和 Ethereum 上运行,并连接到 Swift、RTP、ACH 和支票(美元流通的渠道)。这样,平台通常需要提前存入的资金不再必要。平台可在周六晚上 9 点接受 USDC 并在一秒钟后支付。

全栈卡发行 是缺失的部分。卡程序通常需要三家公司:一家与网络结算的银行、一家批准每笔支付的处理器,以及一家在持卡人付款前提供资金的机构。

几乎没有银行进行批准(这是三者中最技术性的部分)。Column 现在全部自行完成,其卡可由稳定币支持或以稳定币结算。

该批准层每季度处理的每美元中留存的比例越来越低。仅做卡处理的上市公司 Marqeta 报告 6 月季度卡支付量为 $120.4B,同比增长 32%。扣除网络成本后的收入 同比增长 17%,达到 $176.0M。交易量增长速度是收入的两倍,Marqeta 披露 一位客户贡献了 41% 的收入。
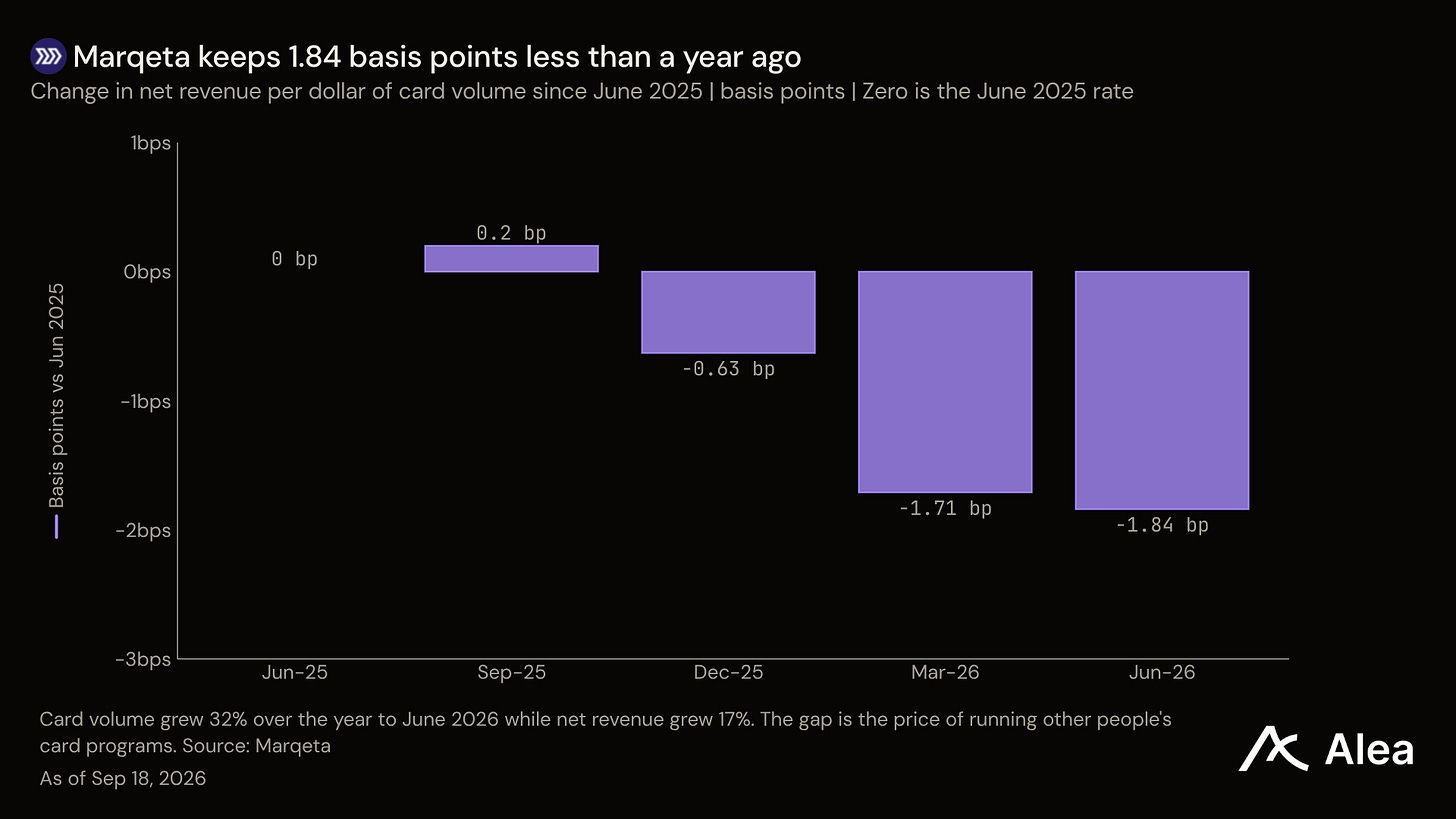
The change in Marqeta's net revenue as a share of the card volume it processes, in basis points, measured against the second quarter of 2025. The line falls steadily to 1.84 basis points below that baseline by the second quarter of 2026.
Marqeta keeps less of every dollar it handles than it did five quarters ago. That is the layer Column’s own card processing now sits in.

全球银行 和 多币种 完成了这一组合。Column 推出 了面向美国境外客户的美元和本地货币账户,支持即时转换,并连接欧洲即时支付系统。它每年已跨境移动数百亿美元。

银行特许权实际带来的好处